Why You Should Never Bid at Property Auction Without a Data-Driven Analysis
Property auctions do not reward speed. They reward precision. In the world of property auction analysis UK, this distinction is everything. Yet most bidders walk into an auction room or log into an online portal believing confidence is enough to secure a good deal.
The atmosphere feels decisive and credible. The catalogue looks professional, the guide prices appear attractive, and other bidders seem experienced. When the price starts rising, it creates a powerful illusion: if everyone else is bidding, this must be a good auction investment.
But auctions reflect competition, not profitability. Demand in the room does not mean the numbers stack up. A property can attract multiple bidders and still fail under proper financial scrutiny.
That illusion is where most losses begin. Not because the market turned or luck ran out, but because the deal was never analysed properly in the first place. Serious investors understand that momentum is noise and data is signal.
Investors who rely on evidence rather than assumptions often study auction performance trends before bidding, using data from our UK Auction House Performance Index to understand which auction houses consistently achieve stronger sale rates and pricing outcomes.
Property Auctions Create Urgency and Artificial Confidence
Auction environments are intentionally structured around momentum:
-
Fixed completion timelines
-
Public competitive bidding
-
Non-refundable 10% deposits
-
Rapid escalation of price
This structure creates urgency. And urgency creates emotional decisions.
The moment bidding starts, logic competes with adrenaline. Investors who would normally spend days analysing a deal compress that discipline into seconds. The rising bids signal “market validation”, even when no one in the room has actually stress-tested the numbers properly.
The result is artificial confidence.
You are not confident because the deal is strong.
You are confident because others are bidding.
There is a difference.
The Psychology of the Guide Price
The guide price is not the value. It is a behavioural anchor.
Many auction lots are marketed at a deliberately attractive guide to stimulate early interest and maximise bidding competition. Investors subconsciously anchor their perception of value to that initial number.
For example:
-
Guide price: £120,000
-
Comparable sold prices: £170,000
The mind immediately sees “£50,000 discount”.
But that perceived discount ignores:
-
Refurbishment costs
-
Bridging interest
-
Auction fees
-
Legal pack risks
-
Refinancing constraints
-
Regulatory exposure
By the time bidding reaches £150,000, many buyers still feel they are getting a deal, because they are anchored to £120,000 rather than analysing the true margin of safety.
This is guide price psychology at work.
Most Property Auction Losses Are Analysis Failures, Not Bad Luck
When auction purchases go wrong, investors often blame:
-
The market
-
The lender
-
The valuer
-
Unexpected costs
-
“Bad timing”
In reality, most losses are not random.
They stem from one of the following:
-
Overestimated end value
-
Underestimated refurbishment costs
-
Over-optimistic refinance assumptions
-
Ignored legal red flags
-
Failure to stress test interest rates
-
No maximum bid calculation
In other words, the loss occurred before the auction even started.
It happened at the analysis stage.
Or more accurately, the lack of it.
Serious Investors Analyse Before They Bid
Professional auction investors approach bidding differently.
They do not ask:
“How high should I go?”
They ask:
“What is the maximum number the data allows?”
Before auction day, they have already:
-
Calculated total acquisition cost.
-
Modelled refurbishment and holding costs.
-
Stress-tested refinancing.
-
Reviewed the legal pack as part of proper property legal due diligence UK investors actually need.
-
Defined a strict maximum bid.
If the bidding exceeds that number, they stop.
No negotiation with themselves.
Don’t put emotional justification.
No “just another £5,000”.
Because serious investors understand a simple rule:
Winning at auction is not success. Buying correctly is success.
What Is Property Auction Analysis?
Property auction analysis is the process of calculating a property’s true acquisition cost, refurbishment budget, financing impact, legal risk and realistic end value before bidding. It determines your maximum bid based on data, not emotion, ensuring the deal works under stress-tested financial assumptions.
Why Property Auctions Are Designed to Trigger Emotion
Property auctions are not neutral environments. They are structured to create speed, competition and commitment within a compressed timeframe. From the countdown clock on online portals to the rapid-fire rhythm of a live auctioneer, the format is built to keep momentum high and hesitation low.
Unlike traditional purchases, auctions remove negotiation buffers. There is no cooling-off period, no prolonged back-and-forth, and no opportunity to renegotiate once the hammer falls. The 10 percent deposit is paid immediately, and contracts are legally binding. That structure intensifies decision-making pressure.
The competitive setting also amplifies social proof. When multiple bidders raise their paddles or click “bid,” it signals demand. Human psychology interprets demand as validation, even though validation does not guarantee profitability. The price rising feels like confirmation rather than risk escalation.
This is why disciplined property auction analysis UK matters. Without a predefined maximum bid and stress-tested numbers, investors can mistake adrenaline for opportunity. Auctions reward preparation, but they are designed to punish hesitation and exploit emotion.
Time Pressure and Competitive Psychology
Auctions compress decision-making into minutes. Once bidding begins, there is little space to pause, re-evaluate numbers or reconsider assumptions. The pace itself creates pressure, and pressure reduces analytical thinking.
Competitive psychology then takes over. Each new bid feels like a challenge rather than a calculation. Instead of asking whether the deal still works, bidders focus on winning. In that moment, beating another investor can feel more important than protecting margin.
Guide Price Anchoring
The guide price is often the first number a buyer sees, and it quietly shapes expectations. Even when investors know it is only a marketing tool, it becomes the psychological reference point. Every bid is subconsciously measured against it.
If the guide is £150,000 and bidding reaches £165,000, it may still feel like value. But the relevant comparison is not the guide price. It is total acquisition cost versus realistic end value. Anchoring to the guide distracts from proper analysis.
Fear of Missing Out (FOMO)
Auctions amplify scarcity. Each lot is presented as a limited opportunity, available only once. The countdown clock or final call reinforces the idea that hesitation equals loss.
Fear of missing out pushes investors to stretch beyond their pre-defined limits. They justify higher bids with optimism about rent, resale value or refinancing. In reality, disciplined investors accept that walking away is often more profitable than overpaying.
The “Below Market Value” Illusion
“Below market value” is one of the most powerful phrases in auction marketing. It suggests instant equity and built-in profit. But market value is not a static number.
A property may appear discounted compared to comparables, yet still fail once refurbishment costs, finance charges and legal risks are factored in. True value only exists after full financial modelling. Without that, “below market value” is simply a headline, not a margin of safety.
Finding an attractive auction lot is only the sourcing stage; analysing a property deal properly means testing the full acquisition cost, refurbishment exposure, finance, legal risk and exit assumptions before deciding how much you can afford to bid.
The Financial Risks Most Property Auction Buyers Underestimate
The hammer price is only the beginning of the financial story. Many auction buyers focus on the winning bid and assume everything else is manageable. In reality, the visible price is often the smallest part of the overall risk.
Auctions compress timelines, which means financial assumptions must already be correct before bidding. There is no time to rethink funding structures, refurbishment budgets or exit strategies after exchange. If the numbers were optimistic going in, the consequences become immediate and expensive.
Financing risk is particularly underestimated. Bridging loans accrue interest monthly, not annually in theory. Delays in refinancing, down valuations or tighter lender criteria can erode projected profit quickly. What looked like a strong margin on paper can disappear within a few months of holding costs.
Refurbishment and compliance costs also surprise many buyers. Structural issues, licensing requirements, lease complications or title restrictions often sit quietly in the legal pack. When discovered late, they turn a “discounted” property into a capital trap.
Most auction losses are not caused by dramatic market crashes. They come from small miscalculations compounded under time pressure. A slightly higher refurb cost, a slightly lower valuation, a slightly slower refinance. Without disciplined analysis, those small gaps become large financial mistakes.
Before bidding, investors should also understand how the purchase will actually be funded, including the deposit, bridging costs, mortgage options and the consequences of missing the completion deadline. In fact, we dedicated a whole article to how to finance an auction property.
True Purchase Cost vs Hammer Price
The hammer price is the most visible number in the room, but it is rarely the true purchase cost. Many investors mentally celebrate the winning bid without calculating what it actually takes to own and stabilise the property.
Beyond the hammer price, you must factor in costs often hidden in the legal documentation, which is why reviewing an auction legal pack guide before bidding is essentia:
-
Stamp Duty Land Tax
-
Auction buyer’s premium and administration fees
-
Legal fees and expedited searches
-
Search indemnity policies
-
Service charge arrears or ground rent arrears
These costs can easily add £10,000 to £25,000 depending on price and complexity. If your margin was only £20,000 to begin with, it has already been eroded before refurbishment even starts.
Mini Example:
-
Hammer price: £180,000
-
SDLT: £9,000
-
Auction fees: £4,000
-
Legal and searches: £3,000
-
Arrears and misc: £4,000
True acquisition cost: £200,000
That £20,000 difference materially changes your return calculation.
Bridging Finance Risk
Bridging finance is commonly used for auction purchases, but it magnifies risk through time sensitivity. Interest is charged monthly and compounds quickly if your exit is delayed.
Consider the pressure points:
-
Monthly interest burn
-
Arrangement and exit fees
-
Valuation and lender fees
-
Dependency on refinance approval
If you borrow £150,000 at 0.9% per month, that is £1,350 per month in interest alone. A three-month delay in refinancing adds over £4,000 in pure cost, excluding fees. If the lender down-values the property, you may need to inject additional capital unexpectedly.
Your entire profit often depends on a smooth refinance. That dependency is risk, not certainty.
Refurbishment Cost Creep
Refurbishment budgets frequently look neat in spreadsheets and unrealistic on site. Initial contractor quotes often exclude contingencies, structural surprises or specification upgrades required to achieve target value.
Common causes of cost creep include:
-
Hidden damp or structural movement
-
Electrical rewiring requirements
-
Boiler replacement
-
Planning or building control upgrades
-
Upgraded finishes to meet valuation expectations
A projected £25,000 refurbishment becoming £35,000 is not unusual. That £10,000 variance directly reduces your margin or increases your capital exposure.
Holding Costs During Delays
Time is a financial variable at auction. Every additional month between purchase and exit adds cost.
Holding costs include:
-
Bridging interest
-
Council tax
-
Insurance
-
Utilities
-
Security or void risk
-
Service charges on leasehold properties
Investors who underestimate these costs often misunderstand the tax treatment of expenses, which is why understanding allowable expenses before you claim is critical.
If your project was modelled at four months but completes in seven, you have three months of unplanned burn. Using the earlier example of £1,350 monthly bridging interest, that is an additional £4,050 before factoring other expenses.
Individually, these costs may appear manageable. Combined, they can eliminate projected profit entirely. This is why disciplined investors calculate total exposure before bidding, not after winning.
What a Proper Property Auction Analysis Should Include
Most auction buyers analyse the visible numbers. Serious investors analyse the full exposure.
A proper property auction analysis UK is not a rough yield estimate or a quick comparison against Rightmove listings. It is a structured breakdown of acquisition cost, capital requirement, financing risk, refurbishment exposure and exit assumptions. Every variable is modelled before a bid is placed.
This is where disciplined investors separate themselves from reactive bidders. They do not rely on guide prices or headline “below market value” claims. They calculate their maximum bid using data, stress testing and defined return thresholds.
At UncommonDeal level analysis, the objective is simple:
If the numbers do not work under conservative assumptions, you do not bid.
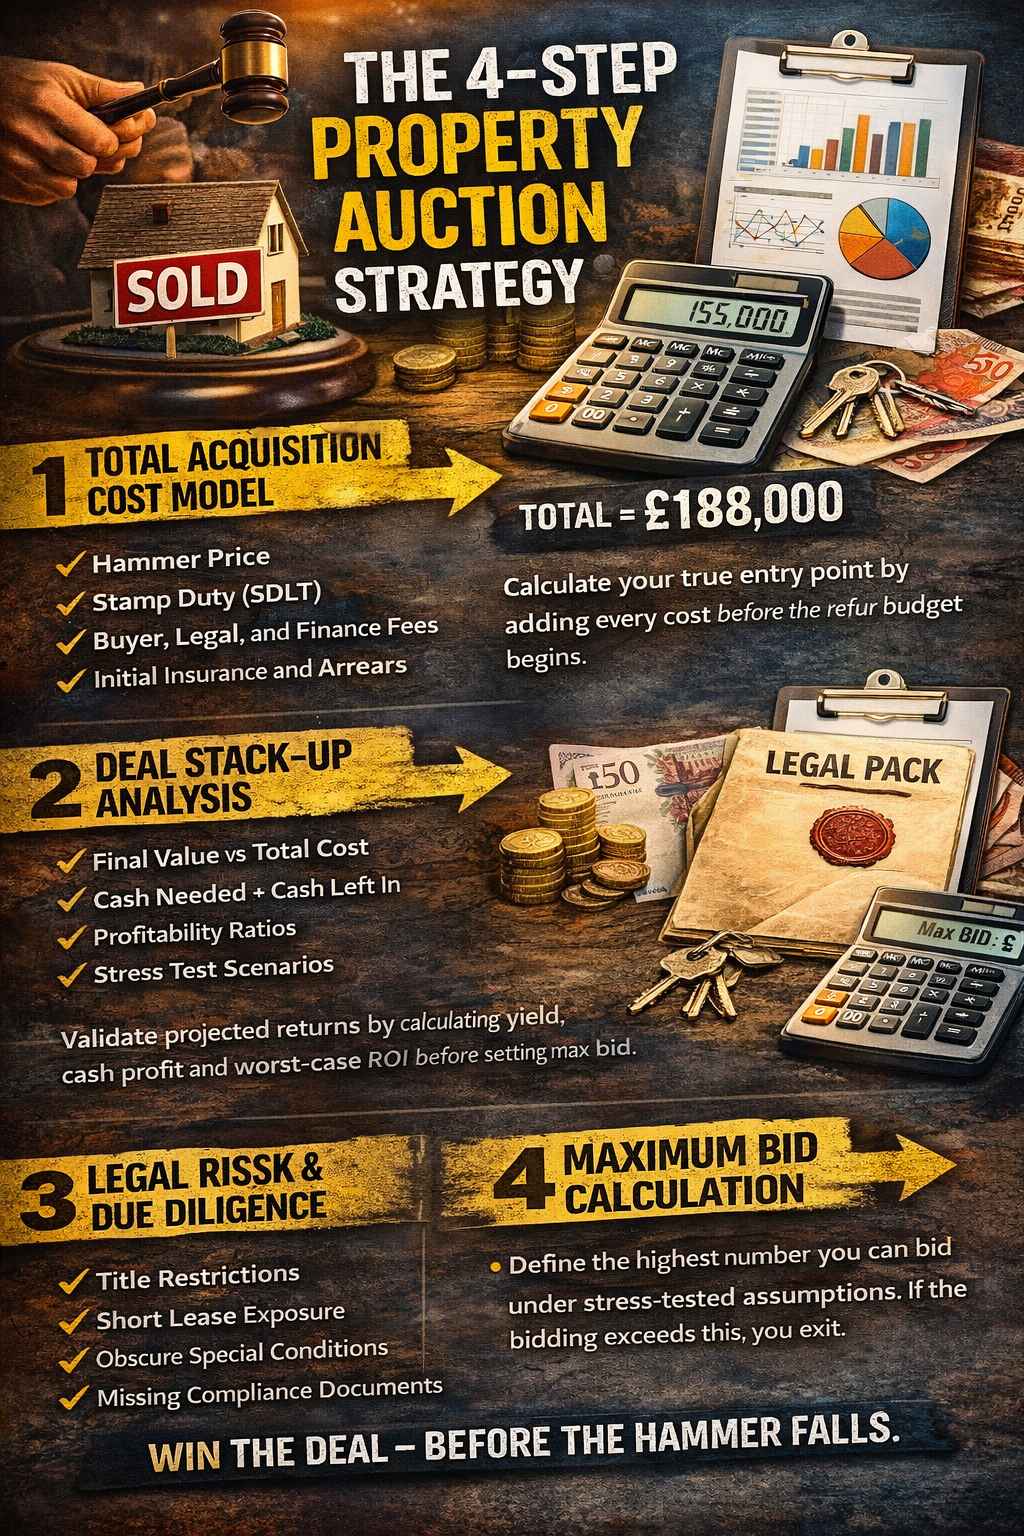
1. Total Acquisition Cost Model
The first step is building a true total acquisition cost model. This goes beyond the hammer price and captures every pound required to take control of the asset.
A proper model includes:
-
Hammer price
-
Stamp Duty Land Tax
-
Auction buyer’s premium and administration fees
-
Legal costs and searches
-
Bridging lender fees and valuation costs
-
Initial insurance and compliance costs
-
Known arrears or title-related liabilities
This produces one critical figure: Total capital exposure on day one.
For example:
-
Hammer price: £170,000
-
SDLT: £8,500
-
Auction fees: £4,000
-
Legal and lender costs: £5,500
Total acquisition cost: £188,000
If your projected end value is £220,000 and refurbishment is £25,000, your real starting position is very different from what the hammer price alone suggests.
Without this model, investors anchor to the wrong number. With it, you see the deal clearly before emotion has a chance to distort it.
2. Deal Stack-Up Analysis
Once total acquisition cost is clear, the next step is stacking the deal properly. This is where many auction buyers stop too early. They look at headline yield and assume the rest will fall into place.
A real deal stack-up answers four core questions:
Cash invested
How much of your own capital is required, including deposit, fees, refurb and buffer? This determines risk concentration and opportunity cost.
True yield
Not the agent’s projected rent divided by hammer price, but sustainable rent divided by total money deployed, which is explained in detail in how to properly analyse a buy-to-let investment.
Cash-on-cash return
Annual net cashflow divided by actual cash invested. This reveals whether the deal justifies the capital tied up.
ROI under stress
What happens if rent is slightly lower, refinance valuation comes in reduced, or costs increase? If your return collapses under small pressure, the margin was never strong.
This is where property auction analysis UK becomes disciplined rather than optimistic. If the numbers only work in a perfect scenario, the bid is too high.
3. Stress Testing Scenarios
Auctions compress timelines, but risk unfolds over months and years. Proper analysis assumes something will not go perfectly.
At minimum, serious investors test:
10% lower valuation
If your refinance valuation drops from £250,000 to £225,000, does the deal still release enough capital? Or are you forced to leave more money in?
3 month refinance delay
Bridging interest continues regardless of your timeline. Can your profit absorb additional monthly finance costs?
Rate rise
If buy-to-let rates increase before completion or refinance, does cashflow remain positive?
Void period
What if the property takes two months to let instead of one? Does your buffer cover it?
Stress testing converts optimism into measurable risk. If the deal fails under modest downside scenarios, your maximum bid must adjust.
4. Legal Risk Scoring
Financial modelling is incomplete without legal risk assessment. Many auction losses originate not from numbers, but from overlooked legal constraints.
Key areas to score include:
Title restrictions
Covenants, access issues, flying freeholds or restrictions that affect resale or mortgageability.
Short lease
Lease length directly impacts valuation, refinance options and future extension cost.
Special conditions
Seller-imposed clauses requiring additional payments, time constraints or cost liabilities.
Missing documents
Absent building regulations certificates, planning permissions or management information packs.
A disciplined approach assigns a risk rating to each issue. If legal exposure increases uncertainty, your maximum bid must decrease accordingly.
Data-driven auction investing is not about being conservative for the sake of it. It is about pricing risk correctly before the hammer falls.
The 3 Types of Auction Buyers (And Who Makes Money)
Not all auction buyers approach risk the same way. On the surface, everyone is bidding on the same property. Underneath, their decision-making frameworks are completely different.
In practice, auction participants usually fall into three categories. Only one group consistently protects capital and builds long-term returns.
The difference is not intelligence or experience alone. It is process.
Some buyers rely on instinct, momentum and perceived discounts. Others use spreadsheets but fail to challenge their own assumptions. A smaller group operates with predefined rules, stress-tested numbers and strict maximum bids.
Auctions do not reward optimism. They reward discipline, because good property deals are built, not chased.
Understanding which category you fall into is critical. Because over time, auction profits do not come from winning more bids. They come from avoiding expensive mistakes. This mirrors the wider principle of how investors actually make money in UK property, where disciplined analysis consistently outperforms excitement or speed.
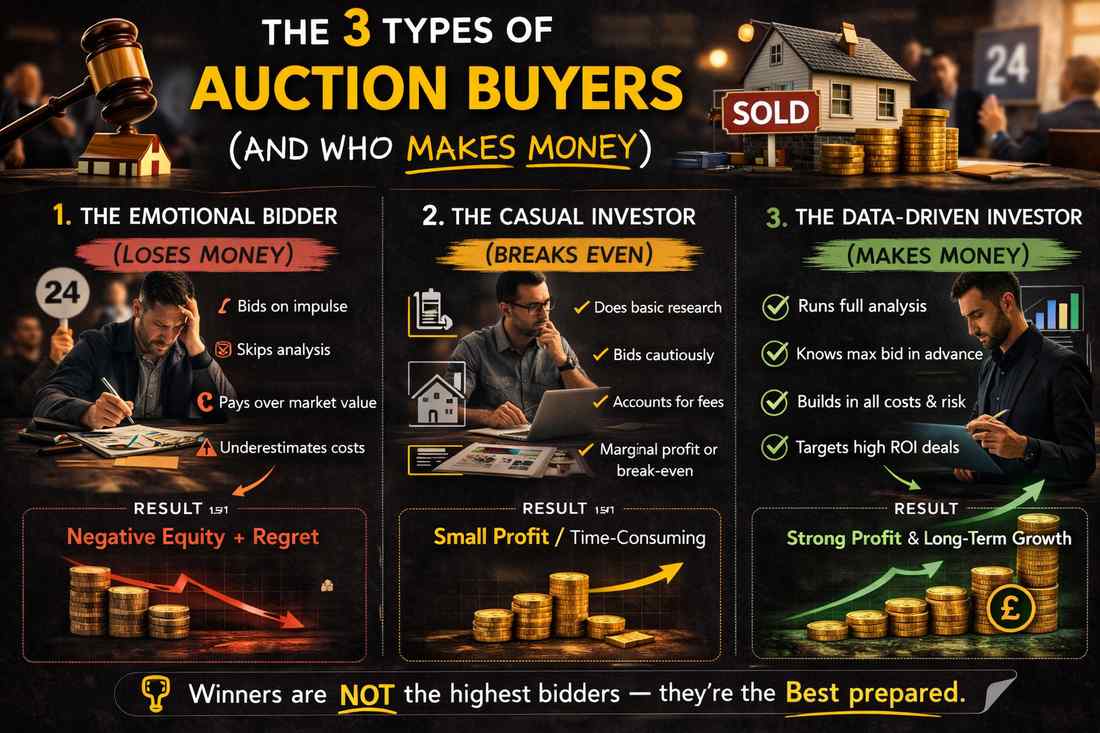
1. The Emotional Bidder
Loses money.
The emotional bidder enters the auction with excitement, not structure. They may have viewed the property and skimmed the legal pack, but they have not built a defined maximum bid from first principles. Their decisions are shaped by momentum in the room.
When bidding accelerates, they stretch. They justify small increases because “it is still below market value” or “rent will cover it.” The deposit is paid quickly, and only afterwards do the real numbers get examined properly.
This buyer does not always lose immediately. But over time, small overpayments, underestimated costs and optimistic refinancing assumptions compound. The margin disappears quietly.
2. The Spreadsheet Investor
Sometimes survives.
The spreadsheet investor is more disciplined. They run numbers, compare rents and calculate yields. They understand that hammer price is not total cost.
However, their weakness is assumption bias. They may rely on best-case valuations, tight refurb budgets or optimistic refinance timelines. The spreadsheet exists, but it is not stress tested.
When everything goes smoothly, this investor can make money. But if valuation comes in lower or refinance is delayed, returns shrink quickly. Survival depends on favourable conditions rather than controlled risk.
3. The Data-Driven Operator
Wins consistently.
The data-driven operator defines the deal before the auction begins. They calculate total acquisition cost, capital required, exit valuation, refinance exposure and downside scenarios. Most importantly, they calculate a strict maximum bid and do not move beyond it.
Not only do they assume friction, but also model delays. In addition, they discount optimistic projections. If the deal still works under pressure, they bid. If it does not, they walk away without hesitation.
This is the positioning behind UncommonDeal. Property auction analysis UK is not about finding more lots. It is about filtering aggressively so only margin-backed opportunities remain.
Winning consistently at auction is not about confidence. It is about controlled exposure. The data-driven operator understands that discipline, not adrenaline, builds long-term capital.
Case Study – Same Property, Two Different Outcomes
Two investors attend the same auction.
Both are interested in the same terraced property with a guide price of £140,000 and an estimated rental income of £1,100 per month.
On the surface, it looks like a strong yield play.
But their approach is very different.
Example Scenario
| Buyer | Approach | Result |
|---|---|---|
| Buyer A | Bids on yield headline | Negative cashflow |
| Buyer B | Full data analysis | Adjusted max bid |
The Numbers
Auction details:
-
Hammer price: £165,000
-
Estimated rent: £1,100 per month
-
Refurbishment: £20,000
-
Bridging at 0.9% per month
-
Refinance assumption: £200,000 valuation
Buyer A – The Headline Yield Decision
Buyer A calculates:
£1,100 × 12 = £13,200 annual rent
£13,200 ÷ £165,000 = 8% gross yield
That looks attractive. They bid and win at £165,000.
But they fail to fully model:
-
SDLT and fees: £12,000
-
Refurbishment: £20,000
-
Total cost: ~£197,000
-
Bridging interest over 6 months: ~£8,000
True total exposure: ~£205,000
The refinance valuation comes in at £190,000, not £200,000.
They cannot pull out as much capital as expected.
With a £150,000 mortgage at 6%, annual interest is £9,000.
After costs, net cashflow becomes marginal or negative.
The deal “looked” strong at the guide price.
It fails under real numbers.
Buyer B – The Data-Driven Operator
Buyer B builds a full property auction analysis UK model before bidding.
They calculate:
-
Total acquisition and refurb cost
-
Bridging interest under 4 and 6 month scenarios
-
Refinance at £190,000 and £200,000
-
Cash left in after refinance
-
Net yield after realistic costs
Their analysis shows:
At £165,000 hammer price, the margin is too thin.
At £155,000, the deal works under stress.
So they set a strict maximum bid of £155,000.
If bidding exceeds that, they walk away.
In this case, Buyer B does not win the lot.
But they also do not inherit a thin-margin, high-risk asset.
The Real Outcome
Buyer A wins the auction.
Buyer B protects their capital.
Over one deal, the difference may look small.
Over ten deals, the compounding effect is massive.
This is the core principle: Auctions reward discipline more than aggression.
Why “Below Market Value†Means Nothing Without Analysis
“Below market value” is one of the most persuasive phrases in auction marketing. It implies instant equity and built-in profit. But market value is not a fixed number. It is conditional.
Without proper property auction analysis UK, “below market value” is just a comparison against an assumption. For a deeper breakdown of what “below market value” really means in practice, it is important to understand how pricing narratives are often constructed. And assumptions can be wrong.
True value depends on multiple underlying factors that many auction buyers overlook.
Market Value Depends on Mortgageability
If a property cannot be financed easily, its market shrinks immediately. Issues such as non-standard construction, short leases, structural concerns or title restrictions can make lenders cautious.
A property worth £220,000 with full mortgageability may only be worth £190,000 if lenders restrict it. Reduced buyer demand lowers practical market value, even if comparables suggest otherwise.
Lease Length
Lease length directly impacts valuation, refinance options and resale liquidity. A short lease can reduce value significantly, particularly as it approaches critical thresholds.
If a buyer ignores lease extension cost or future marriage value and lease extension cost, the apparent discount may disappear entirely. The property might look cheap compared to similar flats, but not once lease risk is priced correctly.
Local Demand
Comparable sale prices do not automatically equal demand for your specific asset. Street-level variation, tenant profile, employment trends and supply dynamics all influence achievable rent and resale speed.
If demand is weaker than assumed, holding periods extend. Extended holding increases finance and operational costs, which reduces real profit even if headline value appears strong.
Regulatory Exposure
Regulation directly affects profitability. Article 4 areas, selective licensing zones, energy efficiency requirements and planning constraints can materially alter a deal’s viability.
If compliance upgrades cost £10,000 or licensing adds ongoing expense, your perceived equity cushion shrinks quickly. Regulation is not theoretical risk. It is financial impact.
Licensing
Certain properties require landlord licensing or planning permission for intended use, as outlined in official government guidance on landlord licensing. If licensing is required but not factored in, costs and delays increase.
Licensing conditions may also restrict occupancy or layout. That can reduce achievable rent and therefore valuation. A property advertised as “high-yield potential” may only achieve that yield under a licensing structure that is not guaranteed.
“Below market value” only means something after risk is priced in. Without analysing mortgageability, lease length, demand strength and regulatory exposure, the discount may be illusionary.
True value is not what the catalogue suggests.
It is what the numbers confirm.
The 10-Minute Auction Rule Serious Investors Follow
Serious auction property investors do not improvise when bidding starts. They operate with a pre-defined checklist. Before raising a paddle or clicking “bid”, they take ten disciplined minutes to confirm that the deal still satisfies their original criteria.
This is not about re-analysing everything in the room. It is about verifying that nothing has changed from the numbers already modelled.
Here is what they confirm.
1. Maximum Bid Calculation
The maximum bid is calculated before auction day, not during it. It is derived from total acquisition cost, refurbishment, finance exposure and realistic end value.
If bidding approaches that number, they stop. No emotional adjustments. No rounding up. If your property auction analysis UK model says the deal only works at £152,000, then £153,000 is already too high.
This is where disciplined use of a structured deal stack-up calculator or a full £29 deal analysis report becomes powerful.
2. Legal Pack Reviewed
A serious investor never bids without reviewing the legal pack or having it reviewed professionally. They confirm:
-
Title restrictions
-
Special conditions
-
Lease length
-
Arrears or liabilities
-
Missing compliance documents
If any legal risk remains unclear, the deal is paused. Speed never overrides clarity.
3. Exit Route Validated
Before bidding, the investor confirms the intended exit:
-
Refinance and hold
-
Flip and resell
They check whether local comparables genuinely support the assumed end value. They ensure demand exists for their intended exit profile, not just theoretical pricing.
4. Refinancing Is Realistic
Refinancing assumptions are stress tested, not hoped for. Investors confirm:
-
Loan-to-value ratios
-
Current lending criteria
-
Realistic stress rates
-
Valuation sensitivity
If a small down-valuation breaks the deal, the maximum bid must be adjusted downward.
5. Worst-Case Return Is Acceptable
Finally, serious investors ask one uncomfortable question:
If this goes slightly wrong, am I still protected?
They examine downside scenarios. Lower valuation. Higher costs. Delays. If the return remains acceptable under conservative assumptions, they bid.
If not, they walk away.
The 10-minute rule is not complicated. It is disciplined confirmation. And over multiple auction purchases, that discipline compounds into consistent profitability while others rely on momentum.
The Cost of One Bad Auction Decision
Auction mistakes are rarely dramatic at the beginning. They feel manageable. The numbers look close enough. The valuation seems achievable. The refinance “should” work.
Then reality unfolds.
Consider a typical scenario:
-
£250,000 hammer price
-
£25,000 deposit paid immediately
-
Bridging finance arranged at 75% loan-to-value
-
Planned refinance at £300,000 post-refurbishment
The investor expects to recycle most of their capital after works are complete.
But the refinance valuation comes in at £270,000, not £300,000. The lender reduces the loan amount accordingly. Suddenly, far more capital is left in the deal than expected.
Bridging continues to accrue interest while the investor searches for alternatives. Costs rise. Pressure builds. With limited options, the property is resold quickly to release capital.
Final outcome:
-
Deposit locked in for months
-
Additional bridging interest paid
-
Legal and resale costs incurred
-
Sold below original expectation
Net loss: approximately £40,000
This is how auction losses typically occur. Not because the property was uninhabitable. Not because the market crashed overnight. But because the original numbers were based on optimism rather than disciplined analysis.
Emotion focuses on winning the lot.
Maths focuses on protecting capital.
Auctions reward those who prioritise the second over the first.
Final Verdict: Analysis First. Auction Second.
Property auctions are not inherently risky. Undisciplined bidding is.
The environment is fast, competitive and emotionally charged by design. But the investors who build long-term capital are not the fastest bidders in the room. They are the most prepared.
Auctions reward discipline, not speed.
Every profitable auction purchase begins before auction day. It starts with total acquisition modelling, stress testing, legal review and a defined maximum bid. By the time bidding begins, the decision has already been made by the numbers.
Data reduces emotion.
When you know your total exposure, downside scenarios and realistic exit value, there is no need for guesswork. You either bid within your limit or you step back. Confidence comes from clarity, not momentum.
Margin of safety matters more than winning.
Winning an auction lot feels decisive. But owning a property with thin margins, refinancing pressure and underestimated risk is expensive. Walking away from a marginal deal is not weakness. It is capital protection.
In property auction analysis UK, the objective is not to win more auctions.
It is to win the right ones.
Analysis first. Auction second.
FAQ: Property Auction Analysis UK
Is buying property at auction risky?
Buying property at auction can be risky because contracts are exchanged immediately and completion deadlines are fixed.
Most risk comes from underestimating total costs, missing legal issues, or relying on optimistic refinance assumptions.
Proper property auction analysis UK reduces risk by stress testing costs and downside scenarios before bidding.
How do you calculate maximum bid at auction?
Start with realistic end value, then subtract refurbishment, finance costs, SDLT, auction fees, legal fees and a contingency buffer.
The remaining figure is your maximum bid. If bidding exceeds that number, you walk away.
Can you pull out after winning an auction?
In most UK auctions, once the hammer falls contracts are legally binding.
Pulling out usually means losing your deposit and potentially facing additional legal consequences.
Do you need a solicitor before auction day?
While not legally required to bid, reviewing the legal pack with a solicitor before auction day is strongly advised,
especially for complex titles, short leases or restrictive special conditions.

Koye Beckley is a UK property investor and founder of UncommonDeal, with practical experience in buy-to-let, property auctions, refurbishment projects and investment deal analysis. Through UncommonDeal, he publishes property market research, property deal sourcing and compliance guidance, investment guides and data-driven analysis to help investors evaluate buy-to-let, BRRR, flip and auction opportunities.






