Property Flips as a Capital Velocity Strategy – BRR
Property flipping in the UK is often misunderstood. It is not a shortcut to fast money, and it is not a passive investment strategy. At its core, a property flip is a capital velocity strategy where returns are generated by buying below value, improving the asset, and recycling capital quickly through resale.
Unlike buy-to-let or BRRR strategies, property flips generate no ongoing income. All profit is realised only when the property is sold. This makes flipping a capital velocity strategy, not a yield strategy.
In practice, flips typically involve:
-
- Purchasing properties with pricing inefficiencies, distress, or execution friction
-
- Adding value through refurbishment, layout optimisation, or compliance fixes
-
- Exiting quickly to recycle capital into the next opportunity
This also explains why flips exist in the first place. They emerge where:
-
- Sellers need certainty and speed
-
- Properties are temporarily unmortgageable or mispriced
-
- The wider market cannot move fast enough to capture the opportunity
Property flipping is often misunderstood because it looks simple on the surface. Buy cheap. Renovate. Sell higher. But the returns do not come from renovation alone. They come from correct pricing, time control, and disciplined exits.
That is why flips succeed or fail on precision, not optimism.
And why they reward operators who understand risk, liquidity, and market timing, not those chasing headline profits.
This article breaks down property flipping as it actually works in the UK, including:
-
- Why flips are treated as a capital-velocity strategy
-
- The specific risks that drive flip returns
-
- When flips work well and when they quietly destroy capital
-
- How flips compare to buy-to-let, BRRR, and development strategies
If HMOs are about managing regulation and yield, property flips are about managing risk, speed, and exit discipline.
Table of Content
What Is a Property Flip in UK Property Investment?
Property flip is a real estate investment strategy where an investor buys a property below its true market value, refurbishes it, and resells it for a profit within a short time frame. The objective is not rental income or long-term ownership. The objective is capital release at exit.
The classic sequence is simple: Buy, Refurbish, Resell.
What matters is not the refurbishment itself, but the pricing gap between acquisition cost and exit value, after all costs and time are accounted for.
At its core, a flip is a short-duration capital deployment, not an income-producing investment.
Property flips sit within a wider set of UK property investment strategies, each defined by how capital is deployed, risk is managed, and returns are realised over time.
Definition of a Property Flip (Buy, Refurbish, Resell)
A property flip follows a simple sequence: buy, refurbish, resell. But the simplicity of the structure often hides what actually creates the profit.
In a UK context, a flip is not about buying any property and “doing it up”. It is about acquiring at a price that already embeds margin, usually because the property cannot currently be sold to the widest pool of buyers. The refurbishment phase exists to remove friction, not to chase cosmetic upgrades for their own sake.
The resell phase is where the strategy is completed. Value is only realised once the property is sold into the open market at a price supported by:
-
- Buyer demand
-
- Comparable evidence
-
- Lender acceptance
Until that point, the flip is unfinished and the profit is theoretical.
Seen properly, a property flip is not three equal stages.
The buy determines whether the deal can work.
The refurb protects the margin.
The resell confirms whether the assumptions were correct.
This is why flipping is less about refurbishment skill and more about pricing discipline and exit realism.
In practical terms, a UK property flip typically involves:
-
- Purchasing below open market value, often due to distress, condition, or complexity
-
- Carrying out targeted refurbishment or remedial works
-
- Reselling once the property meets lender, buyer, and market expectations
The holding period is usually measured in months, not years, and the success of the deal depends on entry price, cost control, and exit timing, not long-term appreciation.
Unlike rental strategies, there is no intention to retain the asset once value has been realised.
Difference Between Flips, BRRR, and Trading Property
Property flips, BRRR strategies, and property trading are often grouped together because they all involve buying and selling property. In reality, they are structurally different approaches with different objectives, risk profiles, and expectations around ownership. Confusing them is one of the fastest ways investors end up applying the wrong assumptions to the wrong strategy.
A property flip is an exit-led capital strategy. The goal is to realise profit in a single transaction and fully release capital. BRRR, by contrast, is a retention-led strategy, designed to recycle capital while keeping the asset and its income long term. Property trading is not a strategy at all, but a classification based on intent and behaviour, typically applied where buying and selling becomes habitual and profit-driven rather than investment-led. Understanding these distinctions matters because each approach is judged, financed, and taxed differently, and each fails for different reasons when execution slips.
Whether a flip is treated as investment activity or trading depends on intent and behaviour, as outlined in HMRC’s badges of trade.
Although often grouped together, flips, BRRR, and property trading are structurally different strategies.
-
- Property flips aim to extract profit in a single transaction through resale. There is no refinance and no retained asset.
-
- BRRR strategies are designed to recycle capital while retaining long-term ownership and rental income.
-
- Property trading is a tax and intent classification, not a strategy, and applies when buying and selling becomes habitual and profit-driven rather than investment-led.
This distinction matters because flips sit between investment and trading. They look like investments, but behave like short-term capital operations, with risk concentrated at entry and exit.
Why Property Flips Exist in the First Place (capital constraints and market inefficiency)
Property flips exist because the UK property market does not move uniformly or efficiently. At any given time, a significant portion of stock cannot be sold to the widest pool of buyers due to condition, complexity, timing pressure, or financing constraints. These frictions create temporary pricing gaps where properties trade below their eventual market value once issues are resolved.
Flippers operate in the space created by those constraints. They deploy capital where others cannot or will not, absorb short-term risk, and convert illiquid or misaligned assets into mortgageable, market-ready stock. The profit is not created by refurbishment alone, but by bridging the gap between constrained sellers and conventional buyers. When capital is scarce, time is limited, or complexity is high, inefficiency widens and flipping margins exist. When those conditions disappear, so do the opportunities.
Property flips exist because the UK property market is not perfectly efficient.
They emerge where:
-
- Sellers prioritise speed or certainty over price.
-
- Properties are temporarily unmortgageable or poorly presented.
-
- Execution risk deters most buyers.
-
- Time pressure creates pricing discounts.
Flippers are effectively paid for:
-
- Moving faster than the market
-
- Solving problems others avoid
-
- Absorbing short-term risk that long-term investors will not
This is why flipping is not about finding “cheap houses”. It is about identifying situations where capital, competence, and timing are misaligned across the market.
When those inefficiencies disappear, flip margins compress quickly.
When they persist, disciplined operators can extract outsized returns, provided they control risk, cost, and time with precision.
Why Property Flips Are Treated as a Capital Velocity Strategy
Property flips are treated as a capital velocity strategy because they are designed to move money, not hold assets. Unlike rental or retention-based approaches, flipping deliberately avoids long-term ownership. Capital is deployed, exposed for a short period, and then released in full at exit. The return is determined not just by how much profit is made, but by how quickly capital can be turned and redeployed.
This makes time a central variable rather than a secondary consideration. With no income during ownership, every additional month held increases cost, risk, and opportunity loss. Successful flips therefore prioritise speed, certainty, and execution discipline over headline margins.
In practice, the faster capital can be deployed, improved, and released, the higher the effective return, even if the headline profit per deal looks modest. When execution slows, a flip stops being a strategy and becomes a prolonged and unproductive capital hold.
Flips Do Not Create Income, They Release Capital
At a structural level, property flips do not produce income during ownership, they temporarily lock capital in anticipation of release at exit. As a result, all holding costs reduce net return, making capital efficiency more important than cashflow generation.
During a flip, the property generates no rental income. Instead, it incurs:
-
- Finance costs
-
- Council tax and utilities
-
- Insurance and security
-
- Opportunity cost on tied-up capital
Every pound invested remains locked until exit. There is no cashflow to offset delays, overruns, or market shifts.
In this sense, a flip is closer to a temporary capital allocation than a traditional investment asset. The property is held only long enough to correct a pricing or condition mismatch and then exited.
Profit Is Realised Only at Exit
In contrast to income-led strategies, profit in a property flip exists only at the point of sale. Until exit completes, margins remain theoretical while costs, risk, and capital exposure remain real.
In a word, profit does not exist until the sale completes and funds are received.
Until then:
-
- Valuations are opinions
-
- Comparables are assumptions
-
- The margin is exposed to cost inflation and market movement
This is why flips feel profitable early but fail late. Small errors compound because there is no income buffer. A two-month delay or a modest softening in buyer demand does not reduce yield. It directly destroys net profit.
Execution discipline matters more than optimism.
Why Speed Matters More Than Yield
As a result, speed becomes the primary driver of performance in a property flip, not yield. Without rental income to offset delays, every additional month held increases cost, risk, and opportunity loss, directly reducing the effectiveness of the strategy.
Because holding the property generates no income, time becomes the primary risk variable.
Successful flippers optimise for:
-
- Acquisition timelines
-
- Refurbishment duration and sequencing
-
- Speed and certainty of exit
A flip that returns £30,000 in four months can outperform a £45,000 flip that takes twelve months once capital recycling and risk are considered.
Experienced operators therefore track:
-
- Capital turns per year
-
- Net profit per month of deployment
-
- Exit certainty, not maximum price
Flipping works when capital moves faster and more precisely than the market.
When execution slows, the strategy collapses into a leveraged bet on price stability.
Property flips are capital velocity strategies because they generate returns by releasing capital quickly at exit, not by producing income during ownership.
The Main Risks That Drive Flip Returns
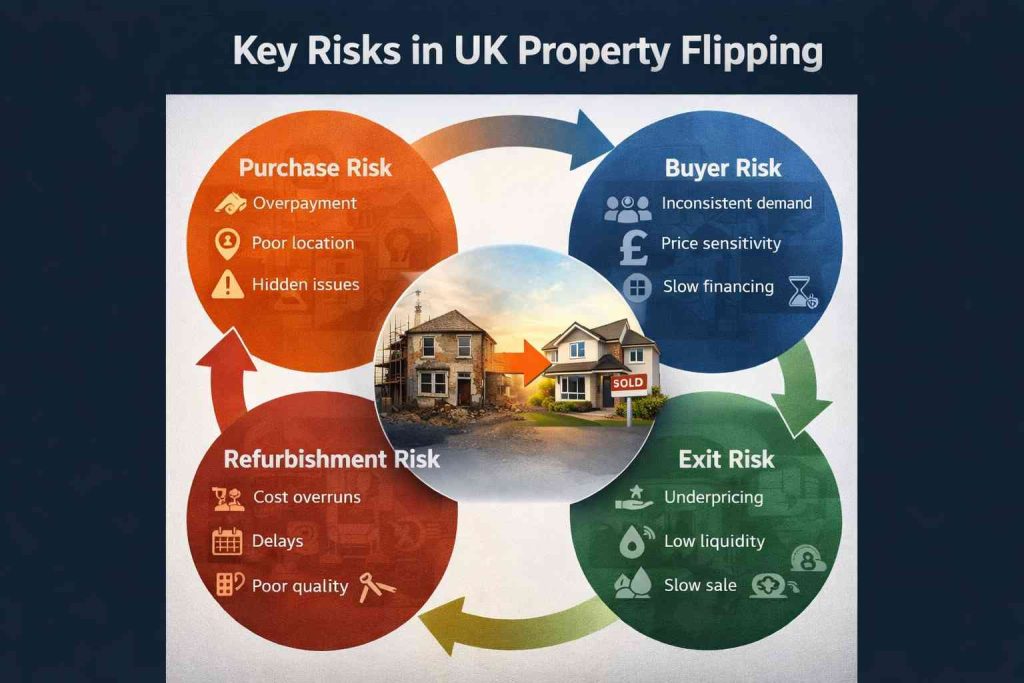
Property flip returns are not driven by refurbishment quality or headline margins. They are driven by a small number of concentrated risks that sit entirely with the investor from the moment of purchase. Because flips generate no income during ownership, these risks are unbuffered. When assumptions are wrong, losses are immediate and permanent.
Many flip failures originate not from refurbishment errors but from overlooked legal and structural risks that only become visible once contracts are exchanged or surveys are commissioned.
Each stage of a flip carries a different exposure. Entry price determines whether a margin exists at all. Execution controls whether that margin survives. Exit conditions decide whether it can be realised. Unlike longer-term strategies, flips offer no ability to wait out mistakes or smooth outcomes over time. The risks outlined below are not incidental to the strategy, they are the mechanism through which returns are created or destroyed.
Because there is no income during ownership, these risks are unbuffered. When they go wrong, they do not dilute returns. They erase them.
Pricing and Acquisition Risk
At the outset, pricing and acquisition risk define whether a property flip can work at all. If the entry price is wrong, no amount of refurbishment efficiency or market optimism can recover the margin later in the process.
The most important decision in a flip is the entry price.
If a property is not bought with sufficient margin below its true resale value, no amount of refurbishment skill can rescue the deal. Overpaying on entry compresses the entire return before work even begins.
Acquisition risk typically shows up as:
-
- Misjudging true market value on exit
-
- Underestimating buyer demand at the resale price point
-
- Ignoring transaction costs and stamp duty in margin calculations
Once contracts are exchanged, this risk cannot be corrected. This is why pricing and acquisition risk is most acute in auction environments, where speed, incomplete information, and competitive bidding amplify the consequences of overpaying.
Refurbishment and Cost Overrun Risk
Beyond acquisition risk, refurbishment and cost overrun risk determine whether an initial margin survives execution. In practice, overruns in scope, time, or pricing reduce profit pound for pound, because flips have no income to absorb errors once works are underway.
Refurbishment risk is where most flip margins quietly disappear.
Most cost overruns trace back to unrealistic refurb cost assumptions, where early estimates are shaped by optimism rather than on-the-ground pricing and sequencing reality.
Cost overruns occur due to:
-
- Incomplete surveys or access limitations
-
- Scope creep once works begin
-
- Labour delays and material price volatility
-
- Discovering compliance or remedial issues late
Because flips rely on fixed-margin exits, every additional pound spent reduces profit pound for pound. There is no long-term upside to compensate for overruns.
Time and Liquidity Risk
Time and liquidity risk are central to property flips because capital is fully exposed until exit. Delays extend holding costs, trap capital longer than planned, and increase the likelihood of forced decisions if liquidity tightens before the sale completes.
Time is the most underestimated variable in a flip.
Delays increase:
-
- Finance interest
-
- Holding costs
-
- Exposure to market shifts
Liquidity risk arises when capital becomes trapped longer than planned, preventing redeployment or forcing compromises on exit pricing.
A flip can be profitable on paper and still fail if capital is not released when expected.
Exit and Buyer Demand Risk
Exit and buyer demand risk sit at the final and most decisive stage of a property flip. All profit depends on selling into active buyer demand at the assumed price point, and even small shifts in sentiment, affordability, or mortgage availability can materially affect the outcome.
Exit outcomes are ultimately shaped by buyer demand and market liquidity, which are established long before purchase through the quality and depth of the underlying deal sourcing.
All flip profits depend on a successful resale.
Exit risk includes:
-
- Changes in buyer sentiment or mortgage availability
-
- Down-valuations by surveyors
-
- Reduced demand at higher price brackets
-
- Competing stock entering the market
Because flips target a defined resale price band, even small shifts in demand can materially affect the outcome.
The market does not reward effort. It rewards alignment with current buyer reality.
Taken together, these risks explain why flips can deliver strong returns in some hands and destroy capital in others. The strategy magnifies precision and punishes assumptions.
Key Takeaway: Flip returns are driven by concentrated risks at entry, execution, and exit. Pricing errors, cost overruns, time delays, and buyer demand shifts directly erode profit because flips have no income buffer to absorb mistakes.
Why These Risks Can Create Strong Returns
The risks in property flipping do not exist by accident. They exist because most participants in the UK property market are structurally unable or unwilling to absorb short-term uncertainty. Mortgage dependence, slow decision cycles, and risk aversion remove large numbers of buyers from this part of the market, leaving pricing gaps where capital can be rewarded for moving quickly.
For disciplined operators, these risks become the source of the return rather than a flaw in the strategy. By pricing accurately, controlling execution, and exiting decisively, flippers are paid for solving problems others avoid. The upside is not driven by leverage or long-term appreciation, but by capturing inefficiency and releasing value faster than the market can respond.
Property flips generate strong returns because the risks are concentrated, visible, and time-bound. Most market participants avoid them not because they are unknowable, but because they require speed, decisiveness, and execution under uncertainty.
Where others step back, margins open up.
Fewer Investors Can Execute Quickly
In practice, only a small portion of the market can move fast enough to execute property flips effectively. As a result, sellers facing time pressure or complexity accept discounts in exchange for speed and certainty, creating the pricing gaps that flips exploit.
Most buyers in the UK property market move slowly. They rely on:
-
- Mortgage approvals
-
- Long chains
-
- Conservative surveys
-
- Risk-averse decision-making
Flippers operate differently. They are able to:
-
- Proceed without chains
-
- Tolerate short-term uncertainty
-
- Complete within compressed timeframes
Speed itself becomes a competitive advantage. Sellers pay for certainty, and that payment shows up as a discount at acquisition.
Distress and Inefficiency Premiums
Consequently, property flip opportunities often arise in situations of temporary distress or market inefficiency rather than long-term decline. In these cases, returns are earned by absorbing short-term complexity and converting constrained assets into stock the wider market is willing and able to buy.
Flip opportunities often sit in areas of temporary dysfunction, not long-term decline.
These include:
-
- Probate sales
-
- Poor presentation or neglect
-
- Unmortgageable conditions
-
- Time-pressured vendors
The premium earned is not for refurbishment work alone. It is for absorbing complexity and short-term risk that the wider market refuses to touch.
Once those frictions are removed, the pricing gap closes rapidly.
Capital Recycling and Compounding
Over time, the real power of property flipping comes from capital recycling rather than single-deal profit. By repeatedly releasing and redeploying capital, disciplined operators can compound returns through speed and repetition, not leverage or long-term holding.
The power of flipping lies in capital recycling, not single-deal profit.
When capital can be:
-
- Deployed
-
- Released
-
- Redeployed multiple times per year
Returns compound through velocity, not leverage.
A disciplined operator turning capital two or three times annually can outperform higher-margin but slower strategies, provided exits remain controlled and losses are avoided.
Returns Reward Precision, Not Leverage
Returns in property flipping reward precision rather than leverage, because margins are fixed and errors compound quickly. As a result, conservative assumptions, tight scopes, and controlled timelines matter more than borrowed scale.
Unlike long-term strategies, flips do not benefit from high leverage.
Leverage amplifies:
-
- Cost overruns
-
- Time delays
-
- Exit risk
Strong flip returns come from:
-
- Conservative assumptions
-
- Tight scopes
-
- Clear exit pricing
-
- Controlled timelines
The market rewards operators who price accurately, execute cleanly, and exit decisively. It punishes those who rely on optimism or borrowed time.
This is why flipping is not about chasing the biggest margin. It is about engineering repeatable outcomes under pressure.
Key Takeaway: The same risks that make flips dangerous also create opportunity. Fewer investors can move quickly, tolerate uncertainty, or execute under pressure, which allows disciplined operators to capture pricing discounts and inefficiency premiums.
When Property Flips Work Well as a Strategy
Property flips work well only when a specific set of conditions are in place. Outside of those conditions, the same mechanics that generate strong returns can quickly turn against the investor. Flipping is not universally effective. It is highly sensitive to capital structure, market behaviour, and execution discipline.
When aligned correctly, flips benefit investors who can deploy capital with buffers, operate in stable micro-markets, and control both scope and timing. The strategy rewards clarity of intent and decisiveness at exit. Where those elements are missing, flips stop being a method for releasing value and become a source of avoidable capital risk.
Flipping is not universally good or bad. It is context-dependent, and success comes from alignment between capital, market, and operator capability.
For Investors With Access to Capital and Contingency
Property flips work best for investors with sufficient capital and contingency, because execution rarely follows a perfect script. As a result, those with liquidity buffers can absorb delays or overruns without being forced into compromised exits.
Flips favour investors who can:
-
- Deploy capital without relying on fragile financing
-
- Absorb delays or overruns without being forced to exit early
-
- Maintain liquidity throughout the project lifecycle
Access to contingency is critical. Because profit is realised only at exit, there must be sufficient buffer to handle surprises without compromising the resale strategy.
Investors operating at the edge of affordability tend to convert manageable issues into fatal ones.
In Stable or Rising Micro-Markets
Property flips rely on predictable buyer demand at a defined price point, which is why market context matters. Hence, stable or rising micro-markets provide the liquidity and pricing confidence needed to exit cleanly and on schedule.
Flip exits depend on active buyer demand at a specific price point.
They work best where:
-
- Comparable evidence is recent and reliable
-
- Buyer demand is consistent
-
- Price sensitivity is predictable
Macro conditions matter less than micro-market behaviour. Even in flat national markets, stable local demand can support clean exits. In softening micro-markets, however, margins compress rapidly.
Where Refurb Scope Is Controlled and Well-Understood
Property flips depend on predictable execution, which makes control over refurbishment scope critical. Therefore, projects with well-understood, repeatable work packages are far more likely to preserve margin than open-ended or highly complex refurbishments.
Successful flips are built on defined, scoped work, not open-ended projects.
They favour:
-
- Cosmetic or layout-driven improvements
-
- Known compliance fixes
-
- Repeatable refurb templates
Complex structural work, planning dependency, or unknown constraints introduce time and cost variability that flips are poorly suited to absorb.
Predictability matters more than ambition.
For Operators Who Prioritise Exit Over Ownership
Property flips favour operators who treat the property as a temporary capital deployment rather than a long-term asset. Therefore, decisions are guided by exit pricing and buyer demand, not personal preference or attachment to the property.
Flips reward operators who:
-
- Design refurbishments for buyers, not personal taste
-
- Price exits realistically, not aspirationally
-
- Sell decisively once value is realised
Emotional attachment, over-specification, or waiting for a “perfect” market erodes returns. Flipping requires the discipline to exit when the numbers work, not when sentiment feels right.
In short, property flips work best when capital is patient, execution is controlled, and exits are treated as the primary objective.
Key Takeaway: Property flips work best when capital is available with contingency, refurb scope is controlled, buyer demand is stable, and the operator prioritises exit over ownership. Predictability and discipline matter more than ambition.
When Property Flips Break Down (And Destroy Capital)
Property flips break down when the assumptions that made the deal viable no longer hold. Because the strategy has no income buffer and a narrow execution window, even small deviations in pricing, timing, or liquidity can have outsized consequences. What might be a manageable issue in a long-term strategy becomes a capital-threatening problem in a flip.
Most flip failures are not caused by a single catastrophic event. They occur through a combination of overpaying, underestimating execution risk, and losing control of time. When capital becomes trapped longer than planned, exits are compromised and forced decisions replace disciplined ones. At that point, the strategy stops releasing value and starts destroying it.
Property flips fail for predictable reasons. Not because the strategy is flawed, but because the margin for error is thin and unforgiving.
When any of the core assumptions break, losses escalate quickly because there is no income to stabilise the position.
Overpaying on Entry
Overpaying on entry undermines a property flip before execution even begins, because the margin is fixed at purchase. In turn, later efficiency gains or market optimism cannot compensate for a price that leaves no room for error.
Most failed flips are broken before the purchase completes.
Overpaying on entry leaves no room for:
-
- Down-valuations
-
- Cost overruns
-
- Slower exits
Once the price is wrong, the strategy becomes a leveraged bet on market movement rather than an engineered outcome. No amount of refurbishment skill can fix a thin entry margin.
Underestimating Refurb Time and Cost
Underestimating refurbishment time and cost erodes flip margins gradually rather than all at once. Consequently, delays and overruns compound holding costs and risk exposure, reducing profit even when the exit price remains unchanged.
Time and cost overruns rarely happen in isolation. They compound.
Common causes include:
-
- Incomplete surveys
-
- Access restrictions
-
- Trades scheduling conflicts
-
- Late discovery of compliance issues
Each delay increases holding costs and exposure to market risk. Because profits are fixed at exit, overruns erode returns directly.
Market Softening Before Exit
Market softening before exit exposes property flips to risk at the most sensitive stage of the strategy. In that scenario, even modest shifts in buyer demand or affordability can force price reductions or extend selling timelines, directly impacting returns.
Flips are exposed to short-term market shifts.
Even modest changes in:
-
- Buyer affordability
-
- Mortgage availability
-
- Competing stock levels
can force price reductions or extended marketing periods.
Unlike rental strategies, flips have no flexibility to wait indefinitely. When demand softens, capital becomes trapped at the worst possible moment.
Liquidity Crunches and Forced Sales
Liquidity crunches occur when capital remains tied up longer than planned and buffers are exhausted. At that point, forced sales replace strategic exits, often locking in losses that could have been avoided with adequate contingency.
The most damaging flip failures occur when liquidity runs out before the exit completes.
This can result from:
-
- Over-leveraging
-
- Multiple flips running concurrently
-
- Delayed sales tying up capital longer than planned
Forced sales rarely achieve target pricing. They convert manageable losses into permanent capital destruction.
This is why flipping is not forgiving. It magnifies both discipline and error.
When done correctly, flips reward precision and decisiveness. When done poorly, they punish optimism, impatience, and thin buffers.
Key Takeaway: Flips break down when entry prices are wrong, costs or timelines overrun, markets soften before exit, or liquidity tightens. Without income to stabilise the deal, small errors escalate quickly into capital loss.
Property Flips vs Other UK Property Investment Strategies
Property flips are often compared to other UK property strategies, but those comparisons only make sense once the strategic differences are clear. Flips are exit-led, short-duration capital strategies, while buy-to-let, BRRR, and development approaches are built around income, retention, or long-term value creation.
They sit in a different strategic lane, defined by concentrated risk, limited flexibility, and decisive exits. Understanding where flips fit relative to other strategies matters because each is driven by different risks, time horizons, and success criteria, and applying the wrong mindset to the wrong strategy is one of the most common causes of underperformance.
This is why flips tend to attract operators rather than landlords. Success depends less on patience or portfolio building and more on pricing accuracy, execution discipline, and the ability to exit cleanly when the numbers work.
Where other strategies allow time to correct mistakes, flips expose them quickly, making strategic alignment more important than deal volume or ambition.
Flips vs Buy-to-Let
Flips and buy-to-let strategies are often compared, but they operate on fundamentally different assumptions. In contrast, buy-to-let relies on income and time to stabilise returns, while flips depend on precise pricing and decisive exits.
Unlike a buy-to-let strategy, which relies on rental income and time to smooth returns, property flips concentrate risk into pricing accuracy and exit execution.
Buy-to-let is an income management strategy. Property flipping is a capital extraction strategy.
Buy-to-let focuses on:
-
- Rental yield
-
- Long-term debt servicing
-
- Income stability over time
Flips focus on:
-
- Entry price discipline
-
- Cost and time control
-
- Certainty of resale
A buy-to-let can survive short-term valuation drops or market noise because income carries the asset. A flip cannot. Once acquired, a flip is fully exposed to exit conditions.
This is why investors who think like landlords often struggle with flips. The instinct to hold, wait, or refinance conflicts directly with a strategy that only works through decisive exits.
Difference: Flips vs BRRR
Flips and BRRR strategies may both recycle capital, but they do so in very different ways. By comparison, BRRR retains the asset and income over the long term, while flips release capital completely through a single exit.
By comparison, the BRRR strategy is designed to retain the asset and income long term, whereas flips release capital entirely through a single, decisive exit.
BRRR strategies are designed to retain assets while recycling capital. Flips are designed to release capital completely.
BRRR relies on:
-
- Rental stabilisation
-
- Valuation uplift
-
- Lender appetite at refinance
Flips rely on:
-
- Buyer demand
-
- Comparable evidence
-
- Market liquidity at exit
Where BRRR spreads risk across time and income, flips compress risk into a narrow execution window. The upside is speed and clarity. The downside is zero flexibility once assumptions are wrong.
This is why BRRR suits investors building long-term portfolios, while flips suit operators focused on capital velocity rather than asset accumulation.
Flips vs Development-Led Strategies
Flips and development-led strategies both involve value creation, but the source and duration of risk differ materially. By contrast, development relies on planning, extended timelines, and multiple external approvals, while flips are execution-driven and exit-focused.
Development strategies are planning- and complexity-driven. Flips are execution-driven.
Development involves:
-
- Planning risk
-
- Extended timelines
-
- Multiple external dependencies
Flips avoid:
-
- Planning uncertainty
-
- Structural transformation
-
- Long approval cycles
While developments can deliver higher absolute returns, they expose capital for much longer periods and rely on factors outside the investor’s direct control.
Flips trade upside potential for speed, simplicity, and repeatability, provided scope remains controlled.
Strategic Positioning Summary
Property flips occupy a distinct position within UK property investment. They are not income strategies, portfolio-building tools, or long-term holds. Instead, they are short-duration, exit-led capital strategies that concentrate risk into pricing, execution, and timing rather than spreading it over years of ownership.
As a result, flips suit investors who value speed, precision, and decisiveness over patience and leverage. When aligned with the right capital structure and market conditions, they can deliver strong returns through capital velocity. When misaligned, they expose weaknesses quickly, making strategic fit more important than deal volume or ambition.
Property flips sit between investment and trading. They:
-
- Generate no income
-
- Retain no long-term assets
-
- Leave no room for indecision
They reward investors who:
-
- Price accurately
-
- Execute quickly
-
- Exit without hesitation
They punish those who:
-
- Over-leverage
-
- Over-complicate
-
- Delay exits waiting for perfect conditions
Flips are not better or worse than other strategies. They are simply more honest. They expose decision quality immediately and make poor assumptions visible very quickly.
Key Takeaway: Property flips differ fundamentally from buy-to-let, BRRR, and development strategies. They do not generate income, retain assets, or tolerate delay. They reward speed, precision, and decisive exits rather than patience or leverage.
Final Verdict: Are Property Flips Worth It?
Property flips are worth it for the right investor, in the right conditions, with the right discipline. They are not a shortcut, a side hustle, or a substitute for long-term investing.
Flips work when they are treated as what they are: a short-duration capital strategy with concentrated risk and no safety net.
They reward:
-
- Accurate pricing on entry
-
- Conservative assumptions
-
- Tight control of time and cost
-
- Decisive exits based on market reality
They punish:
-
- Overpaying
-
- Thin buffers
-
- Optimism dressed up as analysis
-
- Delayed exits waiting for perfect conditions
Unlike buy-to-let or BRRR, flips offer no second chances. There is no rental income to stabilise the asset and no refinance to reset the deal. The outcome is defined by execution quality from day one.
For investors with:
-
- Access to capital and contingency
-
- A clear understanding of their micro-market
-
- Repeatable refurb processes
-
- An exit-first mindset
Flips can deliver strong, repeatable returns through capital velocity rather than leverage.
For everyone else, they are often misunderstood, poorly executed, and expensive lessons in risk management.
The key is not asking whether property flips work.
It is asking whether your capital, temperament, and operating model are suited to a strategy that only pays when everything lines up.
This is why it makes sense to analyse a flip properly before committing capital, rather than relying on assumptions or headline margins to make the decision.
Key Takeaway: Property flips are worth it only when treated as a disciplined, exit-led capital strategy. They reward accuracy and punish optimism. Success depends less on refurbishment skill and more on pricing, timing, and execution control.

Koye Beckley is a UK property investor and founder of UncommonDeal, with practical experience in buy-to-let, property auctions, refurbishment projects and investment deal analysis. Through UncommonDeal, he publishes property market research, property deal sourcing and compliance guidance, investment guides and data-driven analysis to help investors evaluate buy-to-let, BRRR, flip and auction opportunities.
