
How to Spot an Undervalued Property on Rightmove Using Data, Not Guesswork
Spotting an undervalued property on Rightmove is not about finding the cheapest listing in the postcode. It is about identifying properties priced below their evidence-backed, risk-adjusted market value after all costs, constraints, and exit realities are accounted for. Most investors misunderstand that distinction.
Scroll through Rightmove and you will see price reductions, “offers invited,” and listings that have been sitting for weeks. None of those signals, on their own, mean value. They often reflect overpricing, structural issues, poor presentation, lease complications, or simple buyer hesitation.
In the UK market today, margins are tighter, mortgage stress testing is stricter, and regulation is heavier. That means mistakes are more expensive and guesswork gets punished quickly. What looks like a bargain can collapse once you factor in refurbishment costs, financing structure, licensing requirements, or resale demand.
An undervalued property is not one that appears cheap. It is one where:
-
Comparable evidence supports a higher adjusted value
-
The cost of correction is quantifiable and realistic
-
Rental or resale demand is sustainable
-
Risk is priced in, not ignored
This guide will show you how to move from scrolling listings to underwriting deals. You will learn how to establish true market value, adjust comparables properly, model hidden costs, stress test assumptions, and calculate your maximum allowable offer.
Because undervaluation is not found by instinct.
It is proven by numbers.
What Is an Undervalued Property?
An undervalued property is a property that can be purchased below its evidence-backed, risk-adjusted market value after all costs, risks, and exit assumptions have been properly accounted for.
In UK property investing, undervaluation does not simply mean “cheap” or “reduced.” It means the price is lower than what comparable sold evidence supports once refurbishment costs, finance costs, stamp duty, holding costs, and exit friction are deducted.
A property is only genuinely undervalued if:
-
Comparable sold data supports a higher adjusted market value
-
The total cost of correction is accurately quantified
-
Margin remains after stamp duty, finance, and selling costs
-
The deal still works under stress-tested scenarios
If the margin disappears once real-world costs are applied, the property is not undervalued. It is correctly priced for its condition and risk.
In short:
An undervalued property is proven by structured analysis, not perceived by discount.
Why Most Properties on Rightmove Are Not Undervalued
Scroll through Rightmove and it is easy to believe opportunities are everywhere. Price reductions, long listing durations, and below-average asking prices create the illusion of hidden value.
But in most cases, the market is not asleep.
It has already priced in the problem.
The uncomfortable truth is this: if a property looks obviously cheap to you, it has likely looked obviously cheap to hundreds of other buyers too. The reason it has not sold is usually not mystery. It is friction.
Undervaluation is rare.
Correct pricing is common.
1. The Market Has Already Priced in the Obvious Problems
When a property needs heavy refurbishment, has a short lease, backs onto a main road, or suffers from layout issues, buyers notice immediately.
A short lease, for example, can dramatically impact valuation, and understanding how much a short lease really devalues a property is essential before assuming mispricing.
The market adjusts fast.
What looks like a £25,000 discount compared to the best house on the street often reflects:
-
£20,000 of visible works
-
£10,000 of hidden compliance cost
-
Mortgageability constraints
-
Buyer hesitation
The discount is compensation.
Not opportunity.
If the issue is obvious from photos or the description, assume the market has already adjusted for it.
Your job is not to rediscover visible defects.
Your job is to identify mispriced risk.
2. Asking Prices Are Strategic, Not Objective
Estate agents do not price property to reflect intrinsic value.
They price to generate interest, protect vendor expectations, or test demand.
In the light of this, they sometimes overprice; similarly, to drive bidding competition, they sometimes underprice. Lastly, they sometimes follow stale comparables.
This means:
-
A price reduction does not prove undervaluation
-
A “guide price” does not equal fair value
-
A long time on market does not equal desperation
Anchoring to the asking price is one of the biggest analytical errors investors make.
Market value is determined by sold evidence.
Not listing strategy.
3. Spread Illusion Hides Real Cost
Investors often calculate a simple spread:
Comparable value: £220,000
Asking price: £195,000
Perceived margin: £25,000
But this ignores:
-
Stamp duty
-
Legal fees
-
Refurbishment
-
Finance cost
-
Holding drag
-
Selling fees
-
Risk buffer
Once friction is applied, that £25,000 can disappear entirely.
In most Rightmove listings, the market has already adjusted for visible correction cost. What remains is not margin. It is arithmetic without context.
Undervaluation must survive friction.
4. Emotional Bias Creates False Opportunity
When a property fits your budget, strategy, or timeline, you subconsciously want it to work.
You begin:
-
Minimising repair cost
-
Assuming best-case rental figures
-
Ignoring micro-location drawbacks
-
Rationalising market softness
This is not analysis.
It is confirmation bias.
Rightmove encourages emotional scrolling, and understanding the difference between property demand driven by attention vs genuine buyer commitment is critical before assuming interest equals value.
The difference determines profitability.
5. Genuine Mispricing Is Usually Complex
True undervaluation tends to exist where:
-
Legal complexity deters buyers
-
Structural stigma is misunderstood
-
Short-term seller pressure overrides optimisation
-
Micro-market data has not caught up
-
Buyers misinterpret risk
These are not obvious bargains.
They are uncomfortable, technical, and often require deeper analysis.
If a property looks “easy,” it usually is not undervalued.
If it looks complex but modelable, you may be closer.
The Key Principle
Most Rightmove properties are fairly priced for their risk.
Your edge does not come from spotting visible discounts.
It comes from modelling risk more accurately than other buyers.
Step 1 – Establish True Market Value (Not the Asking Price)
If you cannot establish true market value accurately, you cannot identify an undervalued property.
Everything else becomes guesswork layered on optimism.
Most investors make one of three critical errors at this stage:
-
They anchor to the asking price
-
Rely on “similar listings” instead of sold evidence
-
They use postcode averages instead of true comparables
True market value is not what the agent suggests.
It is what comparable buyers have proven they will pay.
That distinction changes everything.
Start With Sold Data, Not Listings
Listings are opinions.
Sold prices are evidence.
If you are serious about spotting undervaluation, your analysis must begin with completed transactions, not live adverts on Rightmove.
The market does not reveal its truth in marketing descriptions.
It reveals it in settled contracts.
When selecting comparables, prioritise:
-
Same street or immediate micro-location
-
Same property type
-
Similar square footage
-
Similar layout
-
Same tenure (freehold vs leasehold)
The closer the match, the stronger the evidence.
If your comparable requires major adjustment, it becomes guidance, not proof.
Adjust Comparables Properly (Where Most Investors Get It Wrong)
Seeing a nearby property sell for £210,000 does not mean yours is worth £210,000.
You must adjust for:
-
Condition standard
-
Extensions or loft conversions
-
EPC rating
-
Lease length
-
Parking and outdoor space
-
Road exposure and positioning
If the property has fewer than 80 years remaining, you must understand how marriage value affects short lease pricing before assuming the discount represents opportunity.
You must earn it.
And earning it costs:
-
Capital
-
Time
-
Risk
Failure to adjust properly is how investors create artificial spreads that disappear later.
Structured Comparable Adjustment Checklist
Before accepting any comparable sale as usable evidence, run it through this filter:
| Adjustment Factor | Comparable Property | Target Property | Adjustment Required? |
|---|---|---|---|
| Property Type & Layout | 3-bed extended terrace | Standard 3-bed terrace | Yes – adjust downward |
| Condition Standard | Fully modernised | Dated / needs upgrade | Yes – deduct full works + risk |
| EPC Rating | C | E | Yes – compliance upgrade cost |
| Lease Length (if applicable) | 120 years | 78 years | Yes – lease extension pricing |
| Parking / Outdoor Space | Driveway + large garden | On-street only | Yes – adjust conservatively |
Why This Checklist Matters
Most investors compare surface similarities.
Serious investors compare structural equivalence.
If three or more rows in that table require material adjustment, your comparable is not directly transferable.
It becomes guidance, not evidence.
And this is exactly where structured valuation tools outperform manual estimation.
Because they force discipline.
Street-Level Variation Matters
Postcode averages hide micro-markets.
Two properties within the same outward code can have very different exit ceilings depending on positioning, exposure, and buyer perception. If you analyse at postcode level instead of street level, you are underwriting noise.
Rightmove filters cannot detect school catchment edges, traffic flow, commercial proximity, or subtle desirability shifts. Buyers feel these differences immediately. Your valuation must reflect them.
Undervaluation sometimes exists at micro-level.
But so does hidden risk.
Create a True Market Value Range, Not a Single Figure
Most investors want one number because it feels precise.
But property valuation is probabilistic.
Professional underwriting produces a range.
For example:
Low evidence: £205,000
Mid evidence: £212,000
High evidence: £220,000
Now the analysis becomes strategic.
If the property is listed at £198,000:
-
Against £205k → thin
-
It is interesting at £212k
-
Against £220k → compelling
Without a range, you cannot model downside.
And without modelling downside, you are not identifying undervaluation.
You are forecasting optimism.
The Shift That Changes Everything
At this point, most investors think they have found a deal.
They see a gap between asking price and adjusted value and assume margin exists.
But that gap is not profit.
It is gross spread before friction.
Step 2 – Quantify the Total Cost of Correction
Establishing market value is only half the equation. The other half is cost. And not just visible cost, but full friction cost.
Most investors stop at refurbishment estimates. Serious investors model total correction as part of a structured framework for how to analyse property deals properly before committing capital.
If Step 1 answered:
What is it worth?
Step 2 answers:
What will it truly cost to realise that value?
Undervaluation only exists if the margin survives both answers.
Entry Friction (Before You Even Start)
Before any works begin, the deal is already absorbing capital.
Entry friction includes:
-
Legal fees and searches
-
Survey and valuation
-
Broker fees
-
Auction buyer premium (if applicable)
These are not optional costs.
They are structural costs.
If your projected margin cannot survive entry friction, it was never margin.
Physical Correction Cost
This is where most investors underwrite incorrectly.
They treat all work as “refurb.”
But work must be classified correctly.
Because classification determines:
-
Risk level
-
Timeline exposure
-
Contingency buffer
-
Finance drag
Cosmetic vs Functional vs Structural
Condition adjustments only work if you classify the work correctly. Rightmove photos mostly show cosmetic.
They rarely reveal functional or structural liabilities. If you price structural risk as a
cosmetic refresh, your entire margin calculation is wrong.
| Category | Typical Examples | What the Market Usually Rewards | Risk Level |
|---|---|---|---|
| Cosmetic | Paint, flooring, light fittings, minor kitchen/bath refresh | Improves first impressions and buyer demand, but rarely increases the ceiling price on its own. | Low |
| Functional | Boiler/heating, electrics upgrades, windows, damp fixes, roof repairs (non-structural) | Protects mortgageability and saleability. Often prevents price discounts rather than creating upside. | Medium |
| Structural | Subsidence, major roof failure, underpinning, layout reconfiguration, major extension works | Can unlock value, but only when the area supports it. Highest overrun risk and biggest timeline exposure. | High |
UncommonDeal rule: If you are not sure whether an issue is functional or structural, model it as structural.
Underwrite pessimistically and let due diligence improve the deal, not the other way around.
Rightmove photos rarely reveal functional or structural liabilities.
If you price structural risk like cosmetic improvement, your margin is fictional.
Finance Cost and Time Risk
Money is not free.
If you are using bridging or short-term capital, you must price:
-
Arrangement fee
-
Interest during works
-
Exit fee
-
Monitoring fees
-
Refinance valuation
Time is not neutral.
Every additional month:
-
Increases interest
-
Holding cost increases
-
Increases exposure to market shifts
Most amateur spreadsheets assume perfect timelines.
Professional underwriting assumes delay.
Finance costs become even more important when the property is bought at auction, where investors may need bridging finance or another short-term funding solution to meet the completion deadline.
Holding Drag
While you are “adding value,” the property is costing you:
-
Council tax
-
Utilities
-
Insurance
-
Security
-
Opportunity cost of tied capital
Small numbers compound over months.
Ignoring holding drag inflates perceived margin.
Exit Friction
If flipping:
-
Estate agent fees
-
Legal fees
-
Negotiation haircut
-
Buyer down-valuation risk
If refinancing (BRRR):
-
Down valuation risk
-
Stress-tested rental coverage
-
Arrangement fees
-
Lender retention risk
Undervaluation must survive exit friction.
Not just acquisition.
Margin After Friction (MAF)
Forget headline spread.
The only number that matters is:
Margin After Friction
Formula logic:
True Market Value (low end of range) – Purchase Price – Total Correction Cost – Risk Buffer = Real Margin.
If Real Margin is:
-
Thin → fragile
-
Dependent on best-case scenario → speculative
-
Dependent on rising market → dangerous
Then the property is not undervalued.
It is hopeful.
Mini Worked Example
Below is a simplified illustration of how “obvious discounts” disappear once friction is modelled.
Worked Example: “£30k Below Market†– Is It?
Adjusted Market Value (Low Range): £220,000
Rightmove Asking Price: £190,000
Perceived Spread
£220,000 – £190,000 = £30,000
Total Correction & Friction Cost
- Stamp Duty & Legal: £6,500
- Refurbishment + Contingency: £25,000
- Bridging Interest & Fees (6 months): £9,000
- Holding & Utilities: £3,000
- Estate Agent & Exit Costs: £4,500
- Risk Buffer: £5,000
Total Cost: £53,000
Margin After Friction
£220,000 – (£190,000 + £53,000) = -£23,000
Conclusion: Not undervalued. Correctly priced by the market.
The £30,000 “discount” was never profit. In fact. it was incomplete analysis.
In addition, the market did not miss this deal; the amateur spreadsheet did.
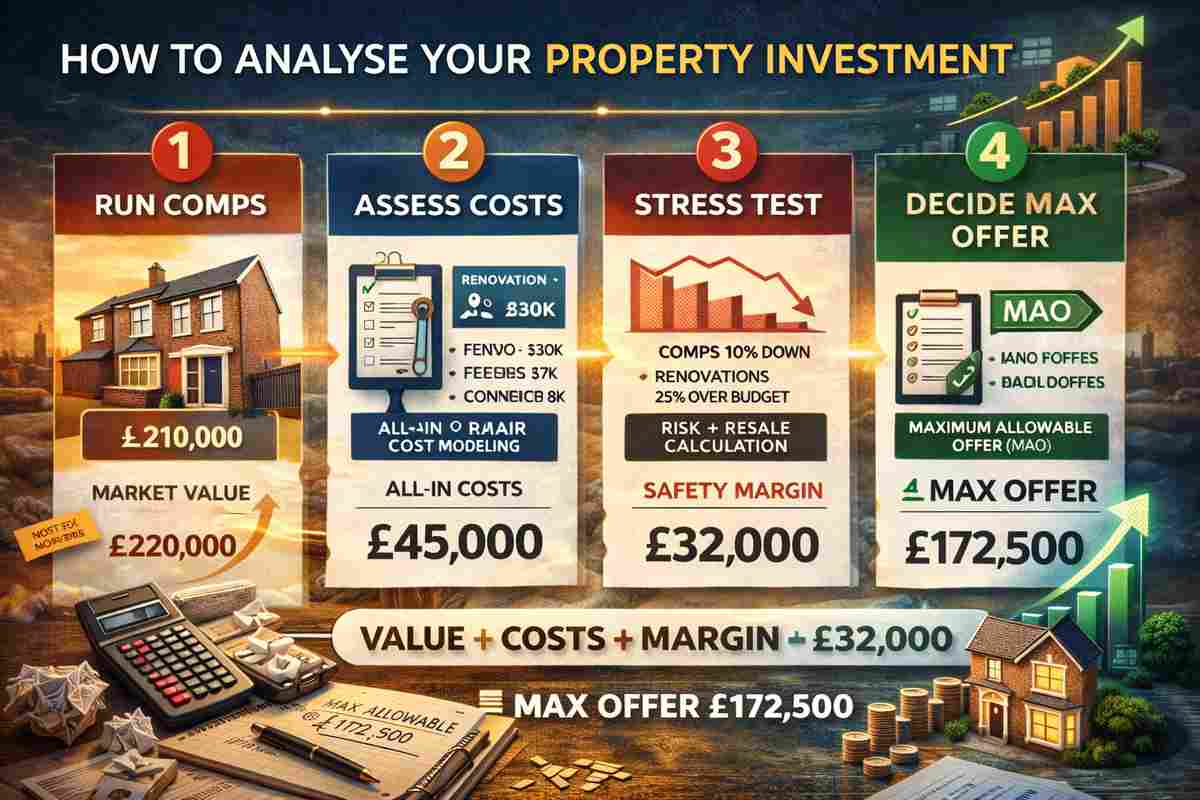
This is why UncommonDeal does not teach “deal spotting”.
It teaches structured underwriting.
Step 3 – Stress Test the Deal (Where Most Analysis Fails)
A property is not undervalued because it works on paper.
It is undervalued if it survives pressure.
Markets soften.
Refurbs overrun.
Valuers disagree.
Buyers negotiate.
Lenders down-value.
If your margin disappears under moderate stress, the deal was never undervalued. It was fragile.
The same principle becomes even more important at auction, where an attractive guide price can encourage investors to bid before establishing the property’s true costs, realistic end value and maximum purchase price. This is why analysing an auction property is an important part of the auction bidding process.
Step 3 is about resilience.
Rental Stress Testing (If Holding or BRRR)
If your strategy involves long-term holding, your numbers must align with a disciplined buy-to-let investment strategy in the UK, not optimistic rental projections.
Do not use:
-
Best-case letting agent estimates
-
“Achievable rent” marketing language
-
Optimistic yield assumptions
Instead:
-
Use conservative rental comparables
-
Stress test interest rates above current products
-
Model rental coverage at lender stress rates
-
Factor in management, maintenance, and void allowance
Ask:
If rent is 10 percent lower than expected, does the deal still work?
Does the cashflow survive if interest rates rise at refinance?
If the deal only works at perfect rent and perfect rates, it is not undervalued.
It is exposed.
Refinance and Down-Valuation Risk
If your strategy relies on refinancing, this is critical.
The risk is not whether you think the property is worth more.
The risk is whether a lender’s valuer agrees.
You must model:
-
Conservative exit valuation (low end of your value range)
-
Possible down-valuation of 5–10 percent
-
Revised loan-to-value impact
-
Reduced capital extraction
If a 10 percent down-valuation breaks your capital recycling plan, your margin was artificial.
Real undervaluation survives conservative valuation.
Market Softening Scenario
Markets do not always rise.
Stress test:
-
5 percent price drop
-
Slower selling period
-
Negotiation haircut from buyer
If flipping:
What happens if you must accept 3–5 percent below your projected exit?
If holding:
What happens if yields compress or demand weakens?
Undervaluation must survive reasonable downside.
Not just upside projections.
Timeline Sensitivity
Time affects everything:
-
Interest cost
-
Holding cost
-
Exposure to market risk
-
Opportunity cost
Model:
-
3-month delay
-
6-month delay
-
Contractor overrun
If a modest delay eliminates your margin, you are not pricing risk correctly.
Serious investors do not assume speed.
They assume friction.
Sensitivity Snapshot Example
Here is a simplified resilience check.
Stress Test Snapshot
Base Case Margin After Friction: £28,000
- 5% Exit Price Reduction → Margin drops to £17,000
- Refurb Overrun (+£8,000) → Margin drops to £20,000
- 3-Month Delay → Margin drops to £22,000
- 10% Down-Valuation on Refinance → Capital Extraction Reduced by £18,000
Observation: Margin remains positive under moderate stress → Potential genuine undervaluation.
This is the difference between:
-
A deal that looks good
-
And a deal that is robust
The Core Principle
Most Rightmove listings fail at Step 3.
Not because the property is bad.
But because the margin only exists in a perfect environment.
Genuine undervaluation survives:
-
Conservative valuation
-
Lower rent
-
Higher cost
-
Slower timeline
If it only works in ideal conditions, it is not undervalued.
It is optimistic.
Step 4 – Calculate Your Maximum Allowable Offer (MAO)
Undervaluation is meaningless if you do not know what to bid. You can model value perfectly, quantify friction accurately, and stress test scenarios conservatively, but without a defined buying threshold, you are still exposed to emotion. The Maximum Allowable Offer is the line between disciplined investing and hopeful negotiation.
MAO forces clarity. It removes anchoring to asking price, neutralises negotiation theatre, and converts your entire underwriting model into one hard number. If the seller will not accept that number, you walk. Not because the property is bad, but because the price eliminates margin.
What Is Maximum Allowable Offer?
Maximum Allowable Offer (MAO) is the highest price you can pay for a property while still preserving your required margin after all costs, friction, and risk buffers.
It is not:
-
The asking price
-
The guide price
-
What you think you can “probably negotiate”
-
What makes the deal feel comfortable
It is the mathematical output of disciplined underwriting.
The MAO Formula
At its core, the logic is simple:
True Market Value (Low End of Range)
– Total Correction Cost
– Required Profit Margin
– Risk Buffer
= Maximum Allowable Offer
The critical detail is this:
You must use the low end of your valuation range, not the optimistic figure.
Professional investors underwrite to survive downside, not chase upside.
Why Most Investors Overpay
Most investors calculate value first and negotiate second.
Serious investors calculate MAO first and negotiate within constraint.
Common overpayment triggers:
-
Emotional attachment to the deal
-
Competition pressure
-
Fear of missing out
-
Anchoring to the seller’s expectation
MAO protects capital from psychology.
If your model says £182,000 and the seller wants £190,000, the answer is simple.
It does not work.
Worked MAO Example
Below is a simplified illustration using the structured framework we have built throughout the article.
Maximum Allowable Offer Calculation
True Market Value (Low Range): £220,000
Total Correction & Friction Cost: £53,000
Required Profit Margin: £25,000
Risk Buffer: £5,000
MAO Calculation:
£220,000 – £53,000 – £25,000 – £5,000 = £137,000
Maximum Allowable Offer: £137,000
If the seller will not accept this, the deal does not meet your criteria.
Notice something important.
The asking price in previous examples was £190,000.
The MAO is £137,000.
That gap explains why most “£30k below market” listings are not opportunities.
They are correctly priced relative to risk.
The Discipline Principle
MAO is not about being aggressive.
It is about being rational.
It forces you to:
-
Price risk properly
-
Protect capital
-
Maintain margin
-
Avoid emotional negotiation
If you do not define MAO before offering, the market defines it for you.
And the market does not prioritise your margin.
Case Study – A “Bargain†That Wasn’t An Undervalued Property
On the surface, the property looked attractive.
It was listed on Rightmove at £189,950. The agent described it as “priced to sell” and “ideal for investors.” Comparable properties on the same road had sold between £215,000 and £225,000 in the past 12 months.
At first glance, it looked like a £25,000 to £35,000 spread.
But spreads are not margin.
Let’s apply the framework properly.
The Listing Snapshot
-
Asking Price: £189,950
-
Property Type: 3-bed mid-terrace
-
Condition: Dated kitchen and bathroom, visible damp in rear wall
-
EPC Rating: E
-
Tenure: Freehold
-
Location: Close to main road, on-street parking only
Agent narrative: “Fantastic opportunity to add value.”
That phrase alone should trigger caution.
Step 1 – True Market Value
True Market Value is the foundation of the entire analysis. If you misprice value at this stage, every calculation that follows becomes distorted. Undervaluation can only exist relative to accurate market evidence.
Comparable Evidence
Three comparable sales within 0.2 miles:
-
3-bed modernised terrace: £222,000
-
A 3-bed updated interior: £218,500
-
3-bed extended, finished: £228,000
However:
-
All were fully modernised
-
Two had upgraded EPC ratings (C)
-
None backed onto a busy road
Adjusted realistic value range:
-
Low: £212,000
-
Mid: £218,000
-
High: £222,000
Conservative underwriting uses the low end.
True Market Value (Low Range): £212,000
Step 2 – Total Cost of Correction
Establishing value is only half the equation. The real test is whether the cost to realise that value leaves margin intact. Step 2 forces you to quantify every layer of friction before you convince yourself the deal works.
Entry Friction
-
Stamp Duty: £3,798
-
Legal & Survey: £2,200
Total Entry: £5,998
Physical Correction
-
Full cosmetic refurb: £18,000
-
Damp investigation & treatment allowance: £6,000
-
EPC improvement (insulation & heating upgrade): £4,000
-
Contingency (15%): £4,200
Total Works: £32,200
Finance & Holding (6 Months)
-
Bridging interest & fees: £8,500
-
Council tax, utilities, insurance: £3,200
Total Finance & Holding: £11,700
Exit Friction
-
Estate agent fees (1.2%): ~£2,500
-
Legal sale cost: £1,200
-
Negotiation haircut allowance: £5,000
Total Exit: £8,700
Total Correction & Friction Cost
Entry: £5,998
Works: £32,200
Finance & Holding: £11,700
Exit: £8,700
Total: £58,598
Step 3 – Margin After Friction
True Market Value (Low): £212,000
Purchase Price: £189,950
Total Correction Cost: £58,598
Total Invested: £248,548
Result:
£212,000 – £248,548 = –£36,548
The £25,000 “spread” was an illusion.
The market had already priced in the required correction.
Step 4 – Maximum Allowable Offer
Using disciplined underwriting:
True Market Value (Low): £212,000
Minus Total Correction: £58,598
Also factor in your required Profit (minimum £25,000)
Minus Risk Buffer (£5,000)
Maximum Allowable Offer: £123,402
Asking price: £189,950
Required offer to make numbers work: £123,402
That gap explains everything.
This was not an undervalued property.
It was a correctly priced problem.
The Lesson
Most investors would have:
-
Negotiated to £180,000
-
Believed they secured a £40,000 “discount”
-
Underestimated damp severity
-
Assumed optimistic resale value
-
Compressed timeline
-
Watched margin evaporate
The framework prevented that.
Undervaluation is not discovered through enthusiasm.
It is revealed through disciplined subtraction.
What Genuine Undervaluation Actually Looks Like
By this point, you may feel that undervaluation is rare. It is. But rare does not mean impossible.
It simply means the market usually prices obvious risk correctly. Genuine undervaluation tends to exist where complexity, timing, or misinterpretation distort pricing, not where defects are visible in photos.
Real opportunity is rarely comfortable. It often requires deeper analysis, technical understanding, or faster decision-making than other buyers are willing to apply.
Let’s look at where it typically appears.
1. Legal or Structural Complexity That Deters Casual Buyers
Properties involving:
-
Title irregularities
-
Restrictive covenants
-
Access issues
-
Short leases
-
Probate delays
-
Minor structural stigma
often scare away inexperienced buyers.
Many of these issues become manageable once you understand the level of property legal due diligence UK investors actually need before committing capital.
The key difference is this:
If the issue is quantifiable and solvable, and the market is pricing it as catastrophic, mispricing may exist.
But if the issue is uncertain and open-ended, the discount may be justified.
Undervaluation exists where risk is misunderstood, not where risk is unknown.
2. Time-Pressured Sales
Speed distorts pricing.
Situations such as:
-
Probate with multiple beneficiaries
-
Divorce settlements
-
Chain collapse urgency
-
Investor liquidation
-
Relocation deadlines
can create pricing below optimisation level.
In these cases, the seller prioritises certainty and speed over maximising value.
However, even here, the numbers must survive structured underwriting. Time pressure alone does not create margin.
3. Micro-Market Anomalies
Sometimes broader comparables lag behind street-level shifts.
Examples:
-
Regeneration impact not fully reflected in sold data
-
School catchment boundary change
-
Infrastructure improvement announcement
-
Shift in rental demand patterns
If your data analysis identifies a ceiling that the seller has not recognised, undervaluation can exist.
But this requires evidence, not speculation about “up-and-coming” areas.
4. Stigma That Is Overpriced
Certain factors can cause exaggerated discounting:
-
Historical damp that has been resolved
-
Minor structural repair already completed
-
Previous sale fall-through
-
Cosmetic neglect creating perception bias
If you can objectively prove the issue has been rectified or overstated, and the market still prices heavy risk, that gap may be opportunity.
Perception-driven discount is different from cost-driven discount.
5. Mispriced Value-Add Potential
Sometimes the market prices a property based on current condition rather than feasible end-state value.
Examples include:
-
Under-utilised loft space
-
Permitted development potential
-
Simple layout reconfiguration
-
EPC improvement unlocking mortgageability
Before pricing EPC improvements, review the official UK EPC requirements for rental properties to ensure compliance assumptions are accurate.
If the uplift is realistic, costed, and supported by evidence-backed ceilings, undervaluation may exist.
But the key word is realistic.
Not hypothetical.
The Pattern You Should Notice
Genuine undervaluation usually shares three characteristics:
-
The issue is clear and quantifiable
-
The correction is costable and manageable
-
Margin survives conservative stress testing
It does not rely on:
-
Market growth assumptions
-
Perfect execution
-
Optimistic rent
-
Hope
It survives structured subtraction.
Why Manual Rightmove Scrolling Is Structurally Weak
Scrolling Rightmove feels productive. Filters give you control. Price reductions feel like opportunity. Long listing durations feel like leverage.
But scrolling is not underwriting.
Manual browsing is built around visibility, not structure. It shows you photos, descriptions, and asking prices. It does not force you to quantify correction cost, stress test assumptions, or calculate margin after friction.
And that is where capital gets exposed.
1. Human Bias Distorts Perception
When you scroll manually, your brain filters for:
-
Price below round numbers
-
“Reduced” tags
-
Attractive layouts
-
Clean presentation
-
Emotional appeal
You begin forming conclusions before modelling the numbers.
Anchoring bias sets in quickly. A property reduced from £230,000 to £199,950 feels like a £30,000 opportunity, even if comparable evidence supports £198,000.
Manual browsing encourages narrative first, numbers second.
Disciplined investing requires the reverse.
2. Inconsistent Comparable Adjustment
When comparing properties manually, investors often:
-
Forget to adjust for lease length
-
Ignore EPC differences
-
Overlook layout variation
-
Skip micro-location nuance
-
Underprice structural risk
Worse, adjustments are inconsistent.
One deal might get a 10 percent contingency.
Another might get 5 percent.
One location might be treated as premium.
Another as average.
Without structure, your underwriting shifts based on mood.
That is not analysis.
That is interpretation.
3. Friction Is Invisible on the Listing Page
Rightmove shows:
-
Asking price
-
Photos
-
EPC rating
-
Basic description
It does not show:
-
True stamp duty impact
-
Finance cost drag
-
Exit fee modelling
-
Negotiation haircut allowance
-
Timeline overrun sensitivity
-
Margin after friction
These are the numbers that determine profitability.
If your analysis stops at asking price vs comparable sale, you are operating with incomplete data.
4. No Built-In Stress Testing
Manual spreadsheets often calculate:
-
Purchase price
-
Refurb cost
-
Exit value
-
Gross profit
But they rarely model:
-
5 percent market drop
-
10 percent down-valuation
-
3-month delay
-
Rental shortfall
-
Overrun contingency
Without stress testing, your deal works in ideal conditions.
Markets are rarely ideal.
5. Speed Replaces Structure
Scrolling creates momentum.
You:
-
Spot something interesting
-
Start imagining the refurb
-
Run quick numbers
-
Begin negotiating
The faster you move, the less structured your analysis becomes.
Serious investors reverse that process.
They structure first.
Then they decide.
The Core Limitation
Rightmove is a marketplace.
It is not a valuation engine.
It is designed to display property.
Not to analyse risk.
If genuine undervaluation requires:
-
Evidence-backed value range
-
Quantified correction cost
-
Margin after friction
-
Stress-tested resilience
-
Defined maximum allowable offer
Then manual scrolling alone is structurally insufficient.
This is where structured underwriting frameworks outperform instinct.
Not because they find more deals.
But because they eliminate weak ones faster.
Final Verdict – Undervaluation Is Proven, Not Found
Undervaluation is not hiding on page three of Rightmove waiting to be discovered. It is not created by price reductions, motivated seller language, or optimistic estate agent descriptions. It is revealed through structured subtraction.
If you cannot quantify value, cost, friction, and stress, you cannot claim undervaluation.
You can only claim hope.
Throughout this guide, the pattern has been clear:
-
Step 1 defines true market value
-
Step 2 quantifies total correction cost
-
Step 3 stress tests resilience
-
Step 4 defines maximum allowable offer
If margin survives all four stages, you may have genuine undervaluation.
If it collapses at any stage, the market likely priced the risk correctly.
The Discipline Principle
Most investors search for deals.
Serious investors eliminate weak ones.
The more disciplined your framework, the fewer properties will qualify. That is not a problem. It is protection.
In today’s UK property market:
-
Margins are thinner
-
Finance is tighter
-
Regulation is heavier
-
Execution risk is higher
Loose underwriting gets punished quickly.
Structured underwriting preserves capital.
What This Means in Practice
If you rely on:
-
Asking price comparisons
-
Headline yield
-
Basic spreadsheets
-
Optimistic rent
-
Best-case exit assumptions
You are not identifying undervaluation.
You are reacting to surface-level signals.
If instead you:
-
Build valuation ranges
-
Classify work properly
-
Model friction and timeline risk
-
Stress test downside
-
Define Maximum Allowable Offer before negotiating
You are operating with discipline.
And discipline compounds.
The Real Edge
The market is efficient at pricing obvious defects.
Your edge does not come from spotting visible problems.
It comes from:
-
Pricing risk more accurately
-
Quantifying friction more realistically
-
Walking away more consistently
-
Buying only when margin survives stress
Undervaluation is rarely obvious.
It is often uncomfortable.
But when it survives structured analysis, it becomes powerful.
Final Principle
Undervaluation is not found through scrolling.
It is proven through numbers.
And the more rigorous your process, the rarer your purchases will be, but the stronger your outcomes will become.
Analyse Rightmove With Structure, Not Instinct
Scrolling Rightmove feels productive.
It is not underwriting.
If undervaluation requires value ranges, correction modelling, stress testing, and a defined Maximum Allowable Offer, then instinct is not enough. Without structure, you are reacting to price signals, not analysing risk.
The Difference Is Discipline
Instinct asks, “Does this look cheap?”
Structure asks:
-
What is the true market ceiling?
-
What will it really cost to get there?
-
Does margin survive downside?
-
What is the maximum safe offer?
If a property fails one of those tests, it is eliminated before capital is exposed.
That is how professionals think.
Before You Make Your Next Offer
Do not negotiate from asking price.
Build the value range.
Price the friction.
Stress test the downside.
Calculate your MAO.
If margin survives, proceed with confidence.
If it collapses, walk away.
Undervaluation is not found by scrolling.
It is proven by structure.
Analyse Rightmove With Structure, Not Instinct
If undervaluation requires value ranges, total correction cost, stress testing, and a clear Maximum Allowable Offer,
manual scrolling is not enough. Use a structured model that forces discipline.
- Build realistic market value ranges from comparable evidence
- Model total friction and correction cost (not just refurb)
- Stress test downside scenarios before you negotiate
- Calculate your Maximum Allowable Offer in minutes
Use the Valuation Engine
See a Sample Output
Tip: Underwrite downside first. Let the deal prove itself.

Koye Beckley is a UK property investor and founder of UncommonDeal, with practical experience in buy-to-let, property auctions, refurbishment projects and investment deal analysis. Through UncommonDeal, he publishes property market research, property deal sourcing and compliance guidance, investment guides and data-driven analysis to help investors evaluate buy-to-let, BRRR, flip and auction opportunities.






