Rental Yield vs Cashflow in UK Property: What Actually Determines Profit?
Most UK property investors talk about yield. Very few properly analyse cashflow.
And that difference is exactly where real profit is either made… or quietly lost.
In today’s higher-interest, compliance-heavy UK rental market, understanding the distinction between rental yield and cashflow is no longer optional. It is fundamental. With mortgage stress testing, Section 24 restrictions, licensing schemes, and EPC upgrade costs reshaping the numbers, relying on headline percentages can destroy an otherwise “good property deal”.
This article breaks down what actually determines profit in UK property investing, and why many investors confuse performance metrics with real financial outcomes.
What We’re Covering in This Article
Before diving into formulas and examples, it is important to clarify what this guide will actually do.
Many articles explain how to calculate rental yield. Some mention cashflow in passing. Very few connect the two in a way that reflects how UK deals behave in the real world.
In this article, we will:
-
Clearly define gross yield, net yield, and cashflow
-
Show how each metric is calculated
-
Explain why yield often looks better than reality
-
Break down the actual drivers of profit in UK rental property
-
Compare real-world scenarios where yield misleads investors
-
Provide a practical decision framework you can apply to your own deals
This is not theory. This is how numbers behave once mortgages, voids, tax, and compliance costs are applied.
For investors interested in more information, we also have the full Rental Yield Guide available within our property guide section.
Why Understanding Yield vs Cashflow Matters for UK Property Investors
In a low-interest environment, yield and cashflow often move in the same direction. A high yield property usually produces strong monthly surplus.
That is no longer guaranteed.
With buy-to-let mortgage rates elevated and affordability rules tightened, a property showing 8 percent gross yield on paper can still produce weak or even negative monthly cashflow once:
-
Mortgage interest is applied
-
Letting fees are deducted
-
Maintenance is budgeted properly
-
Void periods are accounted for
-
Tax is calculated correctly
For UK investors, cashflow determines:
-
Whether you can hold the property long term
-
If refinancing will sustainable
-
Whether you can scale your portfolio
-
Whether stress testing at higher rates will pass
Yield is a screening metric.
Cashflow is a survival metric.
If you are building a portfolio under a limited company structure, refinancing through five-year fixed products, or targeting long-term rental income in markets like Liverpool, Manchester, Birmingham, or the South East, this distinction directly affects risk exposure and scalability.
What Most Investors Get Wrong
The most common mistake is chasing headline yield.
Portals and deal sourcers advertise:
-
“10% Yield!”
-
“High Return Investment!”
But those figures are almost always gross yield, calculated before:
-
Mortgage costs
-
Compliance upgrades
-
Letting fees
-
Major repairs
-
Capital expenditure
-
Tax
A property can show a strong gross yield and still produce weak real profit.
Another mistake is ignoring financing structure. The same property purchased:
-
In cash
-
With 50% LTV
-
With 75% LTV
-
Under a limited company
-
Under personal ownership
…will produce completely different cashflow outcomes.
Investors also underestimate:
-
EPC upgrade costs
-
Article 4 licensing risk
-
Rent controls or reform impacts
-
Void sensitivity in secondary locations
In short, yield gives you a percentage.
Cashflow tells you whether the deal actually works.
What Is Rental Yield?
Rental yield is simply a percentage return based on the relationship between annual rental income and the purchase price (or property value). It gives investors a quick way to compare properties across different price brackets and locations.
Before we compare yield to cashflow, we need to properly define what rental yield actually measures. It is one of the most commonly quoted figures in UK property investing, yet it is often misunderstood.
However, yield is a ratio. It is not a profit calculation. It does not automatically tell you what you will put in your pocket each month. That distinction becomes critical once financing and real-world costs are applied.
Let us break it down properly.
Definition
To understand rental yield correctly, we must distinguish between the two versions that are commonly used: gross yield and net yield. Many listings only show one of these, and that is where confusion starts.
Gross vs Net Yield
Gross rental yield is the simplest and most widely advertised figure. It is calculated using annual rent before any expenses are deducted.
Formula:
Gross Yield (%) = (Annual Rent ÷ Purchase Price) × 100
Example:
-
Purchase price: £150,000
-
Monthly rent: £1,000
-
Annual rent: £12,000
Gross yield = (£12,000 ÷ £150,000) × 100 = 8%
This looks attractive. But gross yield ignores:
-
Mortgage payments
-
Letting agent fees
-
Maintenance
-
Insurance
-
Void periods
-
Compliance costs
That is why many investors move to net yield.
Net rental yield attempts to account for running costs.
Formula:
Net Yield (%) = (Annual Rent – Annual Expenses) ÷ Purchase Price × 100
If annual expenses are £4,000:
Net yield = (£12,000 – £4,000) ÷ £150,000 × 100 = 5.3%
Net yield is more realistic than gross yield. But even net yield still does not account for financing structure in most cases, which is where many investors get misled.
How Yield Is Calculated in Practice
In real-world UK investing, yield is often calculated in one of three ways against:
-
The purchase price only
-
Total project cost including stamp duty and refurb
-
Current market value after works
Each method produces a different percentage.
For example, if you purchase at £150,000 but spend £20,000 on refurbishment, your true capital invested is £170,000. If rent remains £12,000 per year:
-
Yield on purchase price = 8%
-
Yield on total cost = 7.05%
That difference matters.
In BRRR strategies, some investors calculate yield against the post-refurbishment valuation rather than their actual cash left in the deal. While that may make sense for comparison, it does not necessarily reflect real income performance.
Yield is useful for screening and comparison. But it becomes dangerous when treated as a complete profitability metric.
Why Yield Alone Isn’t Enough
Rental yield gives you a percentage snapshot. It does not show you the full financial picture. Once leverage, taxation, and regulatory costs are layered in, yield can become disconnected from real profit.
In today’s UK market, relying solely on yield is one of the fastest ways to misjudge risk.
Let us look at why.
Limitations of Yield
The biggest limitation of yield is that it does not account for financing.
Two investors can buy the same property at the same price, achieve the same rent, and therefore show the same yield. But if:
-
Investor A buys in cash
-
Investor B uses a 75% LTV mortgage at 6% interest
Their cashflow outcomes will be completely different.
Yield also does not account for:
-
Mortgage stress testing requirements
-
Interest rate fluctuations
-
Tax treatment under Section 24
-
Capital expenditure reserves
-
Irregular large repairs
Another limitation is that yield assumes rent remains constant and occupancy is stable. In reality, void periods and tenant turnover directly reduce income.
Yield is static. Cashflow is dynamic.
Common Misconceptions in UK Property
There are several myths that persist in UK investing circles:
Myth 1: High yield means high profit.
Not necessarily. A 10% gross yield property in a weaker area with high void risk may produce less reliable profit than a 6% property in a strong rental location.
Myth 2: Yield is the most important number.
It is important for comparison, but it does not determine whether you can comfortably hold the asset during market shifts.
Myth 3: Net yield solves everything.
Even net yield can ignore financing structure and tax treatment, especially under limited company versus personal ownership.
Myth 4: Southern properties are “bad” because yield is lower.
Lower-yield areas can still generate stable, predictable cashflow depending on financing, tenant quality, and long-term demand strength.
In short, yield tells you how efficient the rent is relative to price.
It does not tell you whether the deal works once real-world costs hit your bank account.
What Is Cashflow?
If yield is a percentage ratio, cashflow is the real-world outcome.
Cashflow measures how much money is left over each month after all expenses are paid. It reflects what actually lands in your bank account, not what looks attractive in a spreadsheet summary.
For UK property investors operating in a higher-rate, compliance-heavy environment, cashflow determines sustainability. It answers a simple but powerful question:
After everything is paid, how much do I actually keep?
Unlike yield, cashflow fully exposes weak financing, underestimated costs, and overoptimistic rent assumptions.
Definition
Cashflow refers to the surplus or shortfall generated by a property after all income and expenses are accounted for.
It is usually measured monthly but can also be assessed annually.
At its simplest:
If the result is positive, the property generates surplus income.
If negative, the investor must top up the difference.
That is the core difference between a deal that scales and a deal that strains your personal finances.
Positive vs Negative Cashflow
A positive cashflow property produces surplus income after:
-
Mortgage payments
-
Letting or management fees
-
Insurance
-
Maintenance provision
-
Compliance costs
-
Service charges (if leasehold)
-
Ground rent (if applicable)
-
Void allowance
-
Tax (depending on structure)
For example:
-
Monthly rent: £1,000
-
Mortgage payment: £650
-
Other costs: £200
-
Net monthly cashflow: £150
That £150 is the true monthly surplus.
A negative cashflow property occurs when expenses exceed rent. This might look like:
-
Monthly rent: £1,000
-
Mortgage payment: £800
-
Other costs: £250
-
Net monthly cashflow: –£50
In this case, the investor must inject £50 per month to hold the property.
Some investors accept negative cashflow if capital growth prospects are strong. But that is a strategic decision, not a mathematical accident.
What Expenses Should Be Included?
Many investors understate cashflow because they forget to include irregular or annualised costs.
A realistic UK cashflow analysis should include:
-
Mortgage repayments (interest-only or repayment)
-
Letting agent fees
-
Maintenance reserve, often 8% to 12% of rent
-
Insurance
-
Licensing fees spread annually
-
Safety certificates
-
Void allowance, often 5% to 8%
-
Tax depending on ownership structure
If these are not included, the “cashflow” figure becomes optimistic rather than accurate.
How Cashflow Drives Profitability
Cashflow determines whether you can hold the property through interest rate cycles, tenant turnover, and regulatory tightening. It is not just about income. It is about resilience.
In the UK market, strong cashflow provides:
-
Buffer against rate increases
-
Capacity to refinance
-
Ability to reinvest into new acquisitions
-
Reduced reliance on personal income
Yield may help you choose a property. Cashflow determines whether you can keep it.
Cashflow vs Capital Growth
Many investors justify weak cashflow by focusing on capital growth.
Capital growth is valuable. But it is unrealised until sale or refinance. Cashflow is immediate.
In areas like parts of the South East where yields are lower, investors often rely on long-term appreciation. In contrast, higher-yield Northern cities may produce stronger immediate surplus but potentially slower capital growth.
The key is balance.
Cashflow protects you in downturns.
Capital growth builds wealth over time.
Relying entirely on one while ignoring the other increases risk exposure.
Why Cashflow Is King for Long-Term Holding
The ability to hold an asset long term is what allows appreciation, rent inflation, and equity growth to compound.
Without stable cashflow:
-
Investors are forced to sell during downturns
-
Refinancing becomes stressful
-
Portfolio growth slows
-
Risk tolerance decreases
Strong cashflow gives optionality. It allows you to wait, refinance strategically, and absorb shocks.
In a market shaped by interest rate volatility, Section 24 tax rules, and increasing compliance obligations, cashflow is not just a metric. It is the stability engine of a property portfolio.
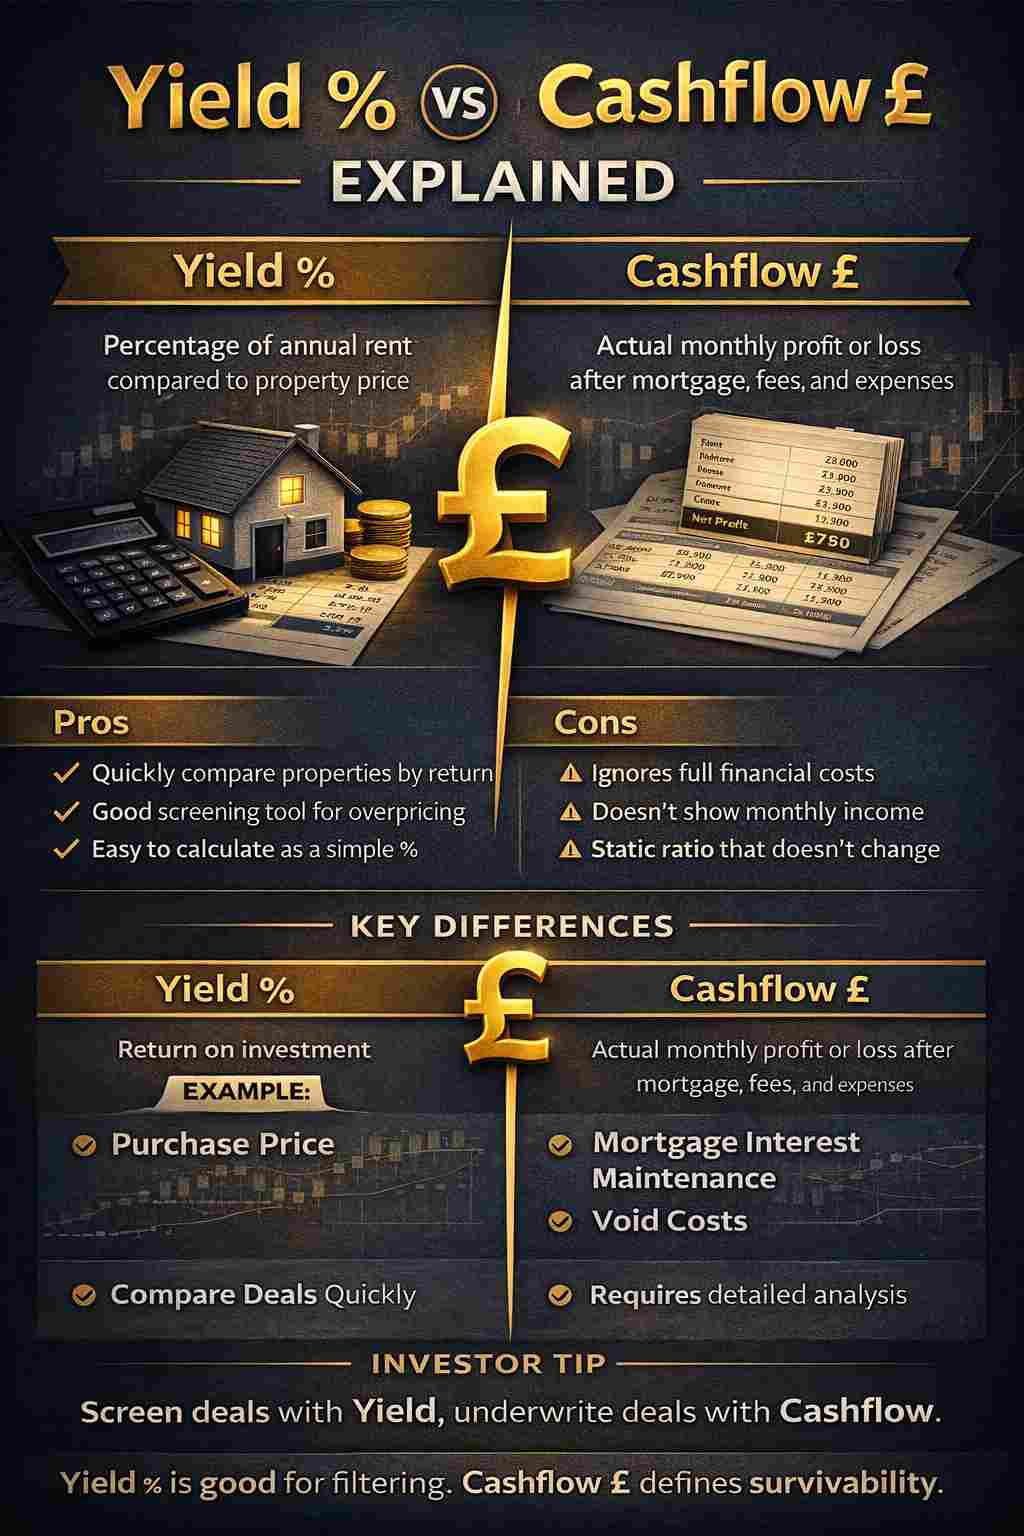
Yield vs Cashflow – The Core Differences
Now that we have clearly defined both rental yield and cashflow, the important question becomes: How do they differ in practical investment decisions?
On the surface, both measure performance. Both relate to income. Both are used in property deal analysis.
But they answer completely different questions.
-
Yield asks: How efficient is the rent relative to the property price?
-
Cashflow asks: How much money do I actually keep each month?
Understanding this distinction is where many investors move from surface-level analysis to disciplined underwriting; especially when choosing between different property investment strategies.
Let us break the differences down clearly.
Side-by-Side Comparison
| Criteria | Rental Yield | Cashflow |
|---|---|---|
| What it measures | Rent as a percentage of price | Surplus income after all costs |
| Type of metric | Ratio / percentage | Pound sterling amount |
| Includes mortgage? | Usually no (gross) | Yes |
| Includes tax? | Rarely | Should |
| Sensitive to interest rates? | No | Yes |
| Shows sustainability? | Not fully | Yes |
| Useful for screening deals? | Yes | Yes, but later stage |
This table shows why relying on only one metric creates blind spots.
Yield Is a Screening Tool
Yield is helpful at the early stage of deal sourcing.
If you are comparing:
-
A £120,000 terrace renting at £900
-
A £200,000 flat renting at £1,000
Yield quickly shows which property is generating stronger rent relative to purchase price.
It allows you to:
-
Compare cities
-
Compare property types
-
Filter deal sourcing leads
-
Filter listings efficiently
That is why estate agents and sourcers highlight it.
But screening is not the same as underwriting.
Yield helps you shortlist.
It does not confirm profitability.
Cashflow Is a Sustainability Tool
Cashflow becomes critical once financing and costs are layered in.
Consider two properties:
Property A
-
Purchase price: £150,000
-
Rent: £1,000 per month
-
Gross yield: 8%
Property B
-
Purchase price: £200,000
-
Rent: £1,100 per month
-
Gross yield: 6.6%
On yield alone, Property A looks superior.
Now add financing at 75% LTV and 6% interest.
If Property A requires heavy maintenance, higher void provision, and stricter licensing compliance, it may produce lower real surplus than Property B.
Cashflow exposes:
-
High leverage risk
-
Thin margins
-
Sensitivity to rate changes
-
Hidden cost structures
It answers the key question: Can this property comfortably survive stress testing?
Why the Same Property Can Look Good on Yield and Weak on Cashflow
This is where many UK investors get caught.
A property in a lower-value area may show:
-
9% gross yield
But if:
-
Mortgage rates rise
-
Void periods extend
-
Maintenance costs spike
-
Tenant turnover increases
The actual surplus can shrink dramatically.
Yield remains unchanged because the formula does not adjust for financing or operational stress.
Cashflow reacts immediately.
That responsiveness makes it the more realistic metric in volatile environments.
The Strategic Difference
The real distinction is not mathematical. It is strategic.
-
Yield helps you compare opportunities.
-
Cashflow determines whether you can hold them.
Yield is about efficiency.
Cashflow is about endurance.
An investor chasing yield alone often accumulates properties that look impressive on paper but require constant top-ups or refinancing pressure.
An investor focused on cashflow builds resilience first, then scales.
The Key Drivers That Actually Determine Profit
Yield and cashflow are outputs.
They are the result of deeper variables working underneath the surface. If you want to understand what actually determines profit in UK property, you must analyse the drivers that shape those outputs.
Many investors focus on percentages without stress testing the components that create them. But in reality, profitability is determined by:
-
Income strength
-
Cost control
-
Financing structure
-
Risk exposure
-
Regulatory burden
Let us break these down properly.
Rental Income
Rental income is the engine of both yield and cashflow. If rent is weak, everything else collapses. If rent is strong and sustainable, margins improve.
But there is a difference between advertised rent and achievable rent.
In many UK markets, particularly in high-demand areas such as parts of Liverpool, Manchester, Birmingham, or commuter belts around London, asking rents may not reflect realistic tenant affordability or long-term stability.
Market Rents vs Achievable Rents
Estate agents often quote “market rent” based on best-case scenarios. However, sustainable rent should consider:
-
Local income levels
-
Tenant profile
-
Comparable properties actually let, not just listed
-
Property condition and EPC rating
Overestimating rent by even £50 per month reduces annual income by £600. That difference directly compresses cashflow and stress-test margins.
In tighter lending environments, conservative rent assumptions protect portfolios.
Costs & Operating Expenses
Income alone does not determine profit. The structure and consistency of costs are equally important.
Many investors underestimate recurring and irregular expenses, which distorts both yield and projected cashflow.
Typical UK operating costs include:
-
Letting agent or management fees
-
Maintenance and repairs
-
Insurance
-
Service charges for leasehold flats
-
Ground rent
-
Safety certificates
-
Licensing fees
Mortgage Interest
For leveraged investors, mortgage interest is usually the largest expense.
Even small changes in interest rates can materially impact monthly surplus. A rate increase from 4% to 6% on a 75% LTV mortgage can wipe out hundreds of pounds per month.
This is why stress testing at higher rates is essential.
Maintenance & Repairs
Maintenance is not optional. It is inevitable.
Older housing stock, common in many high-yield Northern cities, often requires higher ongoing expenditure.
Investors should realistically budget:
-
8% to 12% of annual rent for maintenance
-
Additional reserve for major capital items such as roofs, boilers, or windows
Failing to budget for this creates artificial “positive cashflow” that disappears when repairs arise.
Letting Agent Fees
Management fees typically range from 8% to 15% of rent depending on service level and region.
Self-managing may improve headline cashflow, but time, compliance risk, and tenant management responsibilities must be considered.
Profit is not just financial. It is operational.
Financing Structure
Financing is often the biggest differentiator between a good deal and a fragile one.
Two investors buying the same property can experience completely different outcomes depending on:
-
Loan-to-value ratio
-
Interest rate
-
Interest-only vs repayment mortgage
-
Fixed vs variable rate
-
Personal ownership vs limited company
Higher leverage increases return on equity in good conditions but amplifies risk in volatile ones.
In today’s UK market, conservative leverage often produces more durable portfolios than maximum gearing.
Void Periods
Void periods are rarely discussed in marketing brochures but heavily impact cashflow in reality.
Even one month of vacancy per year reduces annual rent by over 8%.
Voids can arise due to:
-
Tenant turnover
-
Seasonal demand shifts
-
Poor location
-
Oversupply in certain property types
-
Licensing or regulatory delays
Strong tenant demand areas reduce void risk, but no area is immune.
Professional underwriting should include:
-
At least 5% void allowance in strong markets
-
Higher in weaker or student-heavy locations
Yield calculations usually ignore voids. Cashflow feels them immediately.
Taxes & Regulatory Costs
Taxation and compliance are structural profit drivers in the UK.
Changes such as Section 24 restrictions have altered how mortgage interest relief works for individual landlords. HMRC explains how finance cost relief is restricted for residential landlords in its official guidance on property income.
Ownership structure matters.
Limited company landlords are taxed differently from personal investors, affecting net profit outcomes.
Additionally, regulatory costs include:
-
HMO licensing
-
Selective licensing schemes
-
EPC upgrades
-
Electrical and gas safety compliance
-
Fire safety standards
These costs are not optional. They must be built into projections.
Ignoring regulatory impact is one of the fastest ways to overstate profitability.
Capital Expenditure & Long-Term Reserves
Short-term maintenance differs from long-term capital expenditure.
Capital expenditure includes:
-
Roof replacement
-
Structural repairs
-
Full refurbishments
-
Major compliance upgrades
These costs may not occur annually, but when they do, they can eliminate several years of surplus.
A disciplined investor spreads these costs across time by maintaining reserve funds.
Without reserves, even a “positive cashflow” property can become financially stressful during major repair cycles.
The Bigger Picture
Profit in UK property is not determined by a single percentage.
It is shaped by:
-
Sustainable rent levels
-
Realistic cost budgeting
-
Sensible leverage
-
Regulatory awareness
-
Stress-tested assumptions
Yield is the headline.
Cashflow is the outcome.
But the true drivers of profit sit underneath both.
Yield vs Cashflow – Which Matters Most in the UK?
Now that we have broken down the mechanics behind yield, cashflow, and the drivers of profit, the key question becomes:
Which metric should UK investors prioritise?
The honest answer is that both matter. But they matter at different stages of analysis and for different strategic goals.
In the current UK market, shaped by higher interest rates, tighter lending rules, tax restrictions, and increasing compliance costs, cashflow has become significantly more important than it was during the ultra-low-rate years.
Let us examine this through practical scenarios.
Scenario Comparisons
Looking at theory alone can feel abstract. The real clarity comes when we compare how different types of properties behave once financing and costs are applied.
Below are two simplified examples that illustrate how yield and cashflow can diverge.
Scenario A: High Yield, Weak Cashflow
-
Purchase price: £130,000
-
Monthly rent: £1,000
-
Gross yield: 9.2%
On paper, this looks strong.
Now apply:
-
75% LTV mortgage at 6%
-
Letting fees
-
10% maintenance provision
-
5% void allowance
After mortgage payments and operating costs, the monthly surplus may shrink to £50 to £100.
If interest rates increase or an unexpected repair occurs, that surplus can disappear entirely.
The yield remains above 9%, but the real profit margin is thin.
This is common in lower-value, higher-yield areas where maintenance and tenant turnover are higher.
Scenario B: Lower Yield, Stronger Cashflow Stability
-
Purchase price: £220,000
-
Monthly rent: £1,200
-
Gross yield: 6.5%
At first glance, this appears less attractive.
However:
-
Lower tenant turnover
-
Lower maintenance volatility
-
Stronger local employment base
-
More stable demand
Even at similar leverage levels, this property may produce £150 to £250 stable monthly surplus.
While the yield percentage is lower, the risk-adjusted cashflow may be stronger.
This illustrates an important point:
Higher yield does not automatically equal stronger real-world profitability.
Investor Profiles and Strategy Alignment
Which metric matters more often depends on the investor’s objective.
Different strategies prioritise different outcomes.
Buy-to-Let Income Investors
If your goal is monthly income to support lifestyle or replace employment earnings, cashflow must take priority.
These investors need:
-
Predictable monthly surplus
-
Strong stress-testing margins
-
Conservative leverage
-
Reliable tenant demand
Yield helps with screening, but cashflow determines whether the income target is met.
HMO or Value-Add Investors
Higher-yield strategies such as HMOs or refurb-to-let projects often focus on yield expansion.
These investors may accept higher operational complexity in exchange for stronger percentage returns.
However, once financing and management costs are applied, cashflow discipline is still critical.
A 12% gross yield HMO that requires constant reinvestment and high management intensity may produce less net profit than expected.
Long-Term Wealth Builders
Investors focused on capital growth may tolerate thinner cashflow if:
-
The location has strong long-term fundamentals
-
Financing is manageable
-
Risk exposure is controlled
In these cases, yield becomes secondary to long-term appreciation and refinancing potential.
But even here, negative cashflow must be intentional and sustainable, not accidental.
The Practical Conclusion
In the current UK environment:
-
Yield is useful for filtering deals.
-
Cashflow determines resilience.
-
Profit is determined by disciplined underwriting.
If forced to prioritise one metric for sustainability, cashflow wins.
A property with modest yield but stable positive cashflow can survive market shifts.
A high-yield property with fragile margins cannot.
Real UK Example Calculations
Theory is useful. But property investing decisions are made in spreadsheets.
In this section, we will walk through simplified but realistic UK examples to show how yield and cashflow can tell very different stories about the same deal.
These examples assume:
-
75% loan-to-value
-
6% interest-only mortgage
-
Standard single-let buy-to-let
-
Professional management
-
Sensible maintenance and void provisions
The goal is not to produce perfection. It is to demonstrate how numbers behave once layered properly.
Property A: High Yield, Thin Cashflow
This is a typical lower-value property in a higher-yield area.
Purchase price: £140,000
Monthly rent: £1,000
Annual rent: £12,000
Step 1: Gross Yield
Gross Yield = (£12,000 ÷ £140,000) × 100
Gross Yield = 8.57%
This looks attractive.
Step 2: Operating Costs (Annual)
-
Letting/management (10%): £1,200
-
Maintenance reserve (10%): £1,200
-
Insurance & compliance: £600
-
Void allowance (5%): £600
Total non-finance costs: £3,600
Remaining before mortgage:
£12,000 – £3,600 = £8,400
Step 3: Mortgage Cost
Loan amount at 75% LTV:
£140,000 × 75% = £105,000
Interest at 6%:
£105,000 × 6% = £6,300 per year
Step 4: Annual Cashflow
£8,400 – £6,300 = £2,100 per year
Monthly surplus:
£2,100 ÷ 12 = £175 per month
Observations
-
Yield above 8.5%
-
Real monthly surplus: £175
-
A single boiler replacement could eliminate a full year of profit
On headline yield alone, this looks strong.
Under stress, it becomes fragile.
Property B: Lower Yield, Stronger Stability
Now consider a property in a stronger demand area.
Purchase price: £220,000
Monthly rent: £1,200
Annual rent: £14,400
Step 1: Gross Yield
Gross Yield = (£14,400 ÷ £220,000) × 100
Gross Yield = 6.55%
Lower than Property A.
Step 2: Operating Costs (Annual)
-
Letting/management (10%): £1,440
-
Maintenance reserve (8%): £1,152
-
Insurance & compliance: £700
-
Void allowance (4%): £576
Total non-finance costs: £3,868
Remaining before mortgage:
£14,400 – £3,868 = £10,532
Step 3: Mortgage Cost
Loan amount at 75% LTV:
£220,000 × 75% = £165,000
Interest at 6%:
£165,000 × 6% = £9,900 per year
Step 4: Annual Cashflow
£10,532 – £9,900 = £632 per year
Monthly surplus:
£632 ÷ 12 = £53 per month
Side-by-Side Comparison
| Metric | Property A | Property B |
|---|---|---|
| Purchase Price | £140,000 | £220,000 |
| Gross Yield | 8.57% | 6.55% |
| Annual Cashflow | £2,100 | £632 |
| Monthly Surplus | £175 | £53 |
At first glance, Property A appears superior on both yield and cashflow.
But this is where deeper thinking matters.
What These Numbers Don’t Immediately Show
Property A is more sensitive to:
-
Higher tenant turnover
-
Maintenance volatility
-
Interest rate increases
-
Local economic softness
If interest rates rise to 7%, mortgage cost becomes:
£105,000 × 7% = £7,350
New annual cashflow:
£8,400 – £7,350 = £1,050
Monthly surplus drops to £87.50
A further rate increase or unexpected £2,000 repair wipes out the year.
Property B, while thinner in surplus, may sit in a stronger long-term demand area, reducing void and repair volatility.
The point is not that one is better.
The point is this:
Yield gives a surface reading. Cashflow reveals stress sensitivity.
The Bigger Lesson
When analysing deals on UncommonDeal-style spreadsheets or your own models, always calculate:
-
Gross yield
-
Net operating yield
-
Cashflow after finance
-
Stress-tested cashflow at higher rates
Profit is not determined by one percentage.
It is determined by how the property performs when assumptions are challenged.
Practical Tools & Checklists for Analysing Yield and Cashflow
Understanding yield and cashflow conceptually is one thing.
Applying them consistently to real UK deals is another.
Most investors do not lose money because they cannot calculate yield. They lose money because they:
-
Skip full cost breakdowns
-
Overestimate rent
-
Underestimate risk
-
Fail to stress test financing
-
Ignore regulatory drag
This section provides a practical framework you can apply to every deal if you buy at auction, start with our auction buying guides.
The Yield Screening Checklist
Yield is still useful. It just needs to be used correctly.
When screening deals, ask:
-
What is the true purchase cost? Include stamp duty, legal fees, sourcing fees, and refurb.
-
Is the yield calculated against purchase price or total cost?
-
Is the rent assumption conservative or best-case?
-
How does this yield compare to similar streets, not just the wider postcode?
-
Is this yield being inflated by temporary demand spikes?
A disciplined investor should calculate:
-
Gross yield
-
Net operating yield before finance
-
Yield on total cash invested
If a deal only works under gross yield and collapses under net yield, it requires caution.
The Cashflow Underwriting Checklist
Cashflow analysis should be detailed and conservative.
Before progressing with a UK property purchase, confirm:
Income Assumptions
-
Is rent benchmarked against actual let comparables?
-
Have you accounted for at least 4% to 8% void allowance?
-
Is rent dependent on HMO licensing or short-term strategies that carry regulatory risk?
Operating Costs
-
Management fees included?
-
Maintenance reserve realistic for property age?
-
Insurance and compliance fully costed?
-
Service charges confirmed (if leasehold)?
-
Ground rent reviewed?
Financing
-
Loan-to-value confirmed?
-
Interest rate stress tested at least 1% to 2% above current rate?
-
Repayment vs interest-only modelled?
-
Refinancing assumptions realistic?
Tax Structure
-
Personal ownership or limited company?
-
Section 24 impact considered?
-
Corporation tax applied if relevant?
Cashflow must survive conservative modelling.
If it only works under optimistic assumptions, it is not robust.
Stress Testing Framework
Stress testing separates investors who scale from those who stall.
At minimum, test:
-
Interest rate +1%
-
Interest rate +2%
-
One-month additional void
-
£2,000 unexpected repair
If cashflow turns sharply negative under small shocks, risk exposure is high.
Resilient portfolios are built on deals that remain stable even when assumptions deteriorate.
The Decision Framework: Yield vs Cashflow
Use this simple hierarchy when analysing deals:
-
Does the rent make sense relative to price?
If no, reject early. -
Does net operating yield still look reasonable after costs?
If weak, proceed carefully. -
Does cashflow remain positive under conservative stress testing?
If no, reconsider leverage or negotiate price. -
Does the deal align with your strategy?
Income focus requires strong surplus.
Growth focus requires manageable risk.
This layered approach prevents emotional decision-making.
Common Red Flags During Analysis
Be cautious when you see:
-
Yield advertised without cost breakdown
-
Rent assumptions based only on current listing, not let data
-
No maintenance reserve in projections
-
“It will refinance easily” used as justification
-
Cashflow that disappears under small rate increases
If the deal only works under perfect conditions, it is not a good deal.
The Practical Takeaway
Yield helps you compare opportunities quickly.
Cashflow determines whether those opportunities are financially durable.
The right process is sequential:
-
Screen with yield
-
Underwrite with cashflow
-
Stress test aggressively
-
Commit only when margins are real
Common Mistakes UK Investors Make When Comparing Yield and Cashflow
Understanding yield and cashflow is not enough.
The real difference between average and disciplined investors lies in how accurately they apply these metrics in live deals.
In the UK market, many “good looking” deals fail not because the numbers were unavailable, but because they were misunderstood, oversimplified, or selectively interpreted.
Below are the most common mistakes that distort profitability analysis.
Chasing Headline Gross Yield
Gross yield is the most abused metric in UK property marketing.
Listings often advertise:
-
9% yield
-
10% return
-
“High cashflow opportunity”
But these figures are usually based on:
-
Rent before costs
-
No finance
-
No void allowance
-
Purchase price only
-
No compliance provision
A property showing 10% gross yield may fall to 5% net operating yield once realistic expenses are applied.
And once mortgage costs are layered in, the surplus can become minimal.
The mistake is not using gross yield.
The mistake is stopping analysis at gross yield.
Ignoring Financing Sensitivity
Many investors calculate yield correctly but underestimate how sensitive cashflow is to interest rates.
For leveraged investors at 75% LTV:
-
A 1% rate increase can significantly reduce annual surplus
-
A 2% increase can eliminate profit entirely
In the current UK lending environment, assuming rates will remain static is risky.
Every deal should be stress-tested at least 1% to 2% above the initial mortgage rate.
If cashflow collapses under mild stress, the deal carries structural fragility.
Underestimating Maintenance and Capital Costs
Maintenance is not optional.
Older housing stock, particularly common in higher-yield Northern markets, often carries:
-
Roof age risk
-
Boiler replacement risk
-
Damp issues
-
Electrical upgrades
Many projections assume 5% maintenance or less.
In reality, 8% to 12% is more realistic for standard single-lets, and higher for older properties.
The mistake is treating maintenance as occasional rather than inevitable.
Forgetting Voids and Tenant Turnover
Yield calculations rarely include void periods.
Cashflow feels them immediately.
Even one vacant month per year reduces annual rent by over 8%.
In certain property types such as:
-
Student lets
-
HMOs
-
Smaller flats in oversupplied areas
Turnover risk can be higher than expected.
Ignoring void assumptions inflates perceived profitability.
Overlooking Tax Structure Impact
Ownership structure directly affects real profit.
For individual landlords:
-
Section 24 restricts mortgage interest relief
For limited company landlords:
-
Corporation tax applies instead
-
Dividend extraction has implications
Two investors analysing the same property under different structures can reach different profitability outcomes.
The mistake is modelling cashflow pre-tax without considering actual after-tax return.
Confusing Equity Growth With Income
Some investors justify thin or negative cashflow by assuming capital growth will compensate.
Capital growth can build wealth.
But it does not pay the mortgage each month.
If cashflow is consistently negative, holding the property depends on:
-
Personal income stability
-
Refinancing assumptions
-
Market timing
That is a strategic choice, not a default assumption.
Not Matching Metrics to Strategy
Different strategies require different emphasis.
-
Income-focused investors must prioritise stable surplus
-
Growth-focused investors may accept thinner margins
-
Highly leveraged investors must prioritise resilience
The mistake is applying the same yield benchmark to every strategy.
There is no universal “good yield” number.
There is only appropriate alignment between risk, leverage, and objective.
The Core Pattern Behind These Mistakes
Almost every mistake stems from one habit:
- Stopping analysis too early.
- Yield is quick.
- Cashflow is detailed.
- Profit requires depth.
Final Verdict: What Actually Determines Profit?
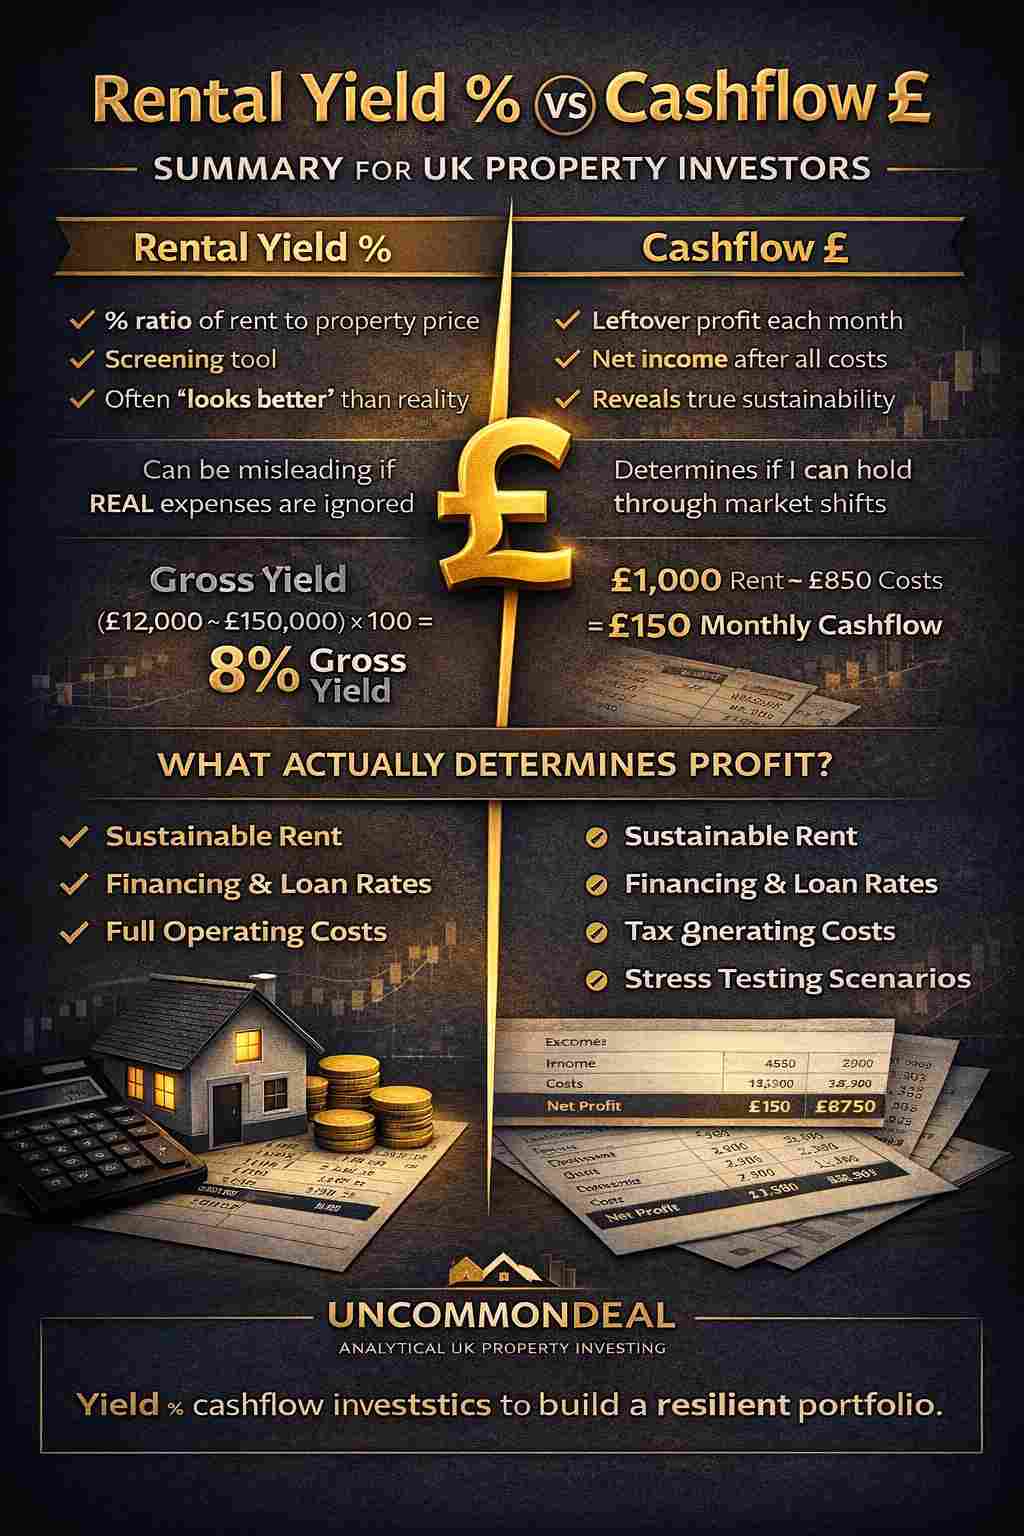
After breaking down yield, cashflow, and the drivers underneath both, the conclusion becomes clear:
Profit in UK property is not determined by a percentage. It is determined by margin strength under stress.
Yield is visible.
Cashflow is tangible.
But durability is what ultimately determines success.
Let us simplify everything into a practical closing framework.
Yield Is the Entry Filter
Rental yield is useful.
It helps you:
-
Compare locations quickly
-
Eliminate obviously overpriced stock
-
Identify potentially efficient rent-to-price ratios
If a property shows extremely weak yield relative to its area, deeper analysis may not even be necessary.
But yield is a filter, not a verdict.
It tells you whether a deal deserves attention.
It does not tell you whether it deserves capital.
Cashflow Determines Survivability
Cashflow answers the question most investors eventually care about:
Can I comfortably hold this asset?
Positive and resilient cashflow allows you to:
-
Survive interest rate shifts
-
Absorb maintenance shocks
-
Navigate regulatory changes
-
Avoid forced sales
-
Scale sustainably
Negative or fragile cashflow turns every external shock into a problem.
In today’s UK market, shaped by:
-
Higher mortgage rates
-
Regulatory tightening
-
EPC upgrade pressure
-
Licensing expansion
Cashflow resilience matters more than ever.
The Real Determinant of Profit
True profitability depends on five interconnected factors:
-
Sustainable rental demand
-
Realistic cost modelling
-
Sensible leverage
-
Tax-aware structuring
-
Stress-tested margins
When those are aligned, yield and cashflow both improve naturally.
When they are ignored, high yield becomes an illusion.
A Simple Decision Framework
Before committing to any UK rental deal, ask:
-
Does the rent make sense relative to purchase price?
-
If the net operating yield remain attractive after full costs?
-
Does cashflow stay positive after conservative stress testing?
-
Could I hold this property for five years without financial strain?
If the answer to any of these is uncertain, the risk is higher than it appears.
The Strategic Mindset Shift
Many new investors chase yield because it feels measurable and impressive.
Experienced investors prioritise durability.
They understand:
-
High yield does not guarantee stability
-
Low yield does not automatically mean poor performance
-
Cashflow discipline compounds over time
The strongest portfolios are not built on the highest percentages.
They are built on repeatable, resilient margins.
Closing Thought
Rental yield is the headline.
Cashflow is the reality.
Profit is determined by how the deal performs when conditions are less than perfect.
If you analyse beyond the percentage and model conservatively, you will make fewer emotional decisions and build a portfolio that survives economic cycles rather than reacting to them.
FAQ: Rental Yield vs Cashflow in UK Property
What is the difference between rental yield and cashflow?
Rental yield is a percentage showing annual rent relative to the property price. Cashflow is the actual monthly surplus (or shortfall) after mortgage, fees, maintenance, voids, and other costs. Yield helps compare deals quickly, but cashflow shows whether the deal is sustainable.
What is a “good” rental yield in the UK?
There is no single number. A “good” yield depends on location, tenant demand, property condition, and your financing. As a rough screen, many investors look for stronger yields outside London, but the real test is whether cashflow stays positive under stress testing.
Can a high-yield UK property still have poor cashflow?
Yes. High gross yield often ignores mortgage interest, management fees, repairs, void periods, licensing, and EPC-related costs. Once these are included, the monthly surplus can be thin or even negative, especially at higher LTVs.
Is cashflow more important than yield for buy-to-let investors?
For most buy-to-let landlords, yes. Cashflow determines whether you can hold the asset through rate changes, repairs, and tenant turnover. Yield is useful for shortlisting, but cashflow decides survivability.
How do I stress test cashflow on a UK deal?
Model higher interest rates (for example +1% and +2%), add a void allowance, and budget realistic maintenance. If the deal becomes negative quickly, the margin is fragile and may need a lower price, lower leverage, or higher rent to work.

Koye Beckley is a UK property investor and founder of UncommonDeal, with practical experience in buy-to-let, property auctions, refurbishment projects and investment deal analysis. Through UncommonDeal, he publishes property market research, property deal sourcing and compliance guidance, investment guides and data-driven analysis to help investors evaluate buy-to-let, BRRR, flip and auction opportunities.






