How To Finance Property Development in the UK For Profit
For many UK property investors, the biggest barrier to progressing into property development is not a lack of experience, ambition, or even deal flow. It is capital — and more specifically, how that capital is structured, deployed, and protected.
One of the most persistent questions in UK property circles is deceptively simple:
“How do people actually finance property development?”
It is common to see investors who have renovated several properties, managed tenants for years, and understand refurbishment work thoroughly, yet feel unable to move into development or flipping at scale. Savings feel slow. Equity feels tied up. And much of the advice online feels detached from real-world constraints.
A common profile looks like this:
- Experience renovating properties to a good standard
- Several years as a landlord
- Recently bought or renovated their own home
- Single income household
- Limited ability to save quickly
- Available capital: £25,000–£30,000 (or sometimes £50,000)
- Interest in flipping or small development projects
- Willing to operate through a limited company.
This article answers a practical question: how to finance a property project in UK. Not in theory, but in practice — using realistic assumptions, conservative numbers – run the numbers before committing capital, and two very common starting points: £25,000 vs £50,000 of available capital.
The First Reality Check: Capital Doesn’t Create Deals — Structure Does
One of the biggest misunderstandings in property is that more capital automatically means better opportunities.
It doesn’t.
What capital really buys is:
- Flexibility
- Time
- Margin for error
With less capital, deals must be:
- Smaller
- Cleaner
- Faster
- Less complex
With more capital, the room to absorb mistakes increases — but discipline still matters.
Understanding this difference early prevents expensive learning curves later.
Why Financing Is the Biggest Barrier for UK Property Developers
Property development compresses risk. Unlike long-term buy-to-let investing, where time can smooth mistakes, development concentrates financial exposure into a short window. Funding structure therefore matters as much as the deal itself.
Experience vs capital: why many investors get stuck
Many investors reach a plateau after buy-to-let or small refurbishments. They know how to manage builders, handle refurb budgets, and deal with agents. What they lack is sufficient capital to bridge the gap between opportunity and execution.
Experience alone does not unlock finance. Lenders and investors fund structures, not stories. Without a financeable framework, experience remains underutilised.
Why savings alone rarely fund property development
Relying on savings alone is increasingly unrealistic. Stamp duty, rising living costs, recent purchases, and single-income households often limit capital accumulation. As a result, most developers rely on leverage, partnerships, or both.
The Most Common Ways Property Development Is Financed in the UK
In practice, nearly all small-to-medium UK property developments are financed through a combination of the following routes.
1. Bridging finance for Flipping (Buy-Refurb-Sell) projects
Bridging finance is a short-term funding solution commonly used by property investors to acquire, refurbish, and resell property quickly. It is particularly suited to flipping projects, where speed, flexibility, and the ability to add value are more important than long-term borrowing costs.
Unlike traditional mortgages, bridging loans are designed to work around time pressure and property condition. They are frequently used where a property is uninhabitable, unmortgageable, or purchased at auction—situations where mainstream lenders either cannot lend or cannot move fast enough.
Equally important for purchasing property at the auction, you will need to perform a proper auction property due diligence.
2. Joint ventures with private investors
Joint ventures (JVs) are a common way to finance property development and flipping projects in the UK, particularly where one party has capital and the other has experience, deal access, and execution capability.
In a typical JV structure, a private investor provides the funds required to purchase and refurbish a property, while the developer or operator contributes the deal sourcing, project management, refurbishment oversight, and exit execution. Profits are then shared according to a pre-agreed formula.
This approach allows projects to move forward without relying on bank finance, while enabling investors to participate in property deals they may not have the time, expertise, or appetite to run themselves.
3. Development finance for larger projects
Development finance is a specialist funding solution used for heavier refurbishments, conversions, and multi-unit schemes that go beyond the scope of standard bridging loans. It is commonly applied to projects such as office-to-residential conversions, large HMOs, block refurbishments, and ground-up or near-ground-up developments.
Unlike bridging finance, development loans are released in stages, known as drawdowns. The lender advances funds at key milestones—typically purchase, strip-out, structural works, first fix, second fix, and completion—following inspections by a monitoring surveyor. This staged approach reduces lender risk while ensuring capital is deployed in line with progress.
Loan terms are usually 12–24 months, with funding based on a combination of loan-to-cost (LTC) and loan-to-gross development value (LTGDV). In the UK, lenders may fund up to 60–70% of GDV and 80–90% of total build costs, subject to experience, planning status, and project viability.
Development finance is most suitable for projects with:
- Clear planning or permitted development rights
- Detailed build costings and professional reports
- A defined exit strategy (sale or refinance)
Interest is typically charged monthly and often rolled up, helping manage cashflow during construction. However, arrangement fees, monitoring costs, and professional requirements mean development finance is more complex than bridging.
For experienced developers, development finance enables larger, higher-value projects to proceed without tying up excessive equity. Used correctly, it allows capital to be leveraged efficiently while maintaining control over scale, timing, and exit strategy.
The UK planning gives more information on planning consideration for developers.
4. Using equity from existing property
Many developers fund new projects by unlocking equity from property they already own. Instead of bringing in outside investors or expensive short-term finance, they use the value built up in existing assets to move forward.
This is typically done through a remortgage, further advance, or second charge loan. A remortgage replaces the existing loan with a larger one, releasing cash in the process. A further advance increases borrowing with the same lender, while a second charge allows additional borrowing without disturbing the main mortgage—useful when current rates are favourable.
Using equity can feel more comfortable because the funding is usually cheaper than bridging finance and doesn’t involve sharing profits. It also gives developers full control over decisions, timelines, and exits.
That said, it’s not risk-free. The property used as security is exposed, and cashflow must comfortably support the higher borrowing. If a project overruns or the exit is delayed, the pressure is felt across the wider portfolio, not just the new deal.
This approach works best when:
- The existing property has strong equity and stable income
- The new project has clear margins and realistic timelines
- The developer understands the knock-on impact on their portfolio
Used carefully, recycling equity can be one of the most efficient ways to grow—allowing developers to leverage past success to fund future opportunities, without overcomplicating the finance stack or diluting returns.
5. Partnering with capital-rich, time-poor individuals
Not all funding relationships in property are formal joint ventures or hands-off investments. Many successful deals come from partnering with people who have capital available but little time or desire to run projects themselves.
These individuals are often business owners, professionals, or long-term landlords who understand property but don’t want the day-to-day work. Rather than acting as passive investors, they become working partners, contributing funds while staying involved at a high level—reviewing decisions, agreeing strategy, and sharing responsibility for outcomes.
The strength of these partnerships usually comes from trust and alignment, not complex structures. Returns are often agreed in simple terms: a clear split of profits, repayment of capital first, or a defined return linked to the success of the project. Because both parties have “skin in the game,” incentives are naturally aligned.
This approach can be more flexible than traditional finance. There’s often less pressure from fixed deadlines, fewer fees, and more room to adapt if timelines or market conditions shift. It also tends to work well for repeat projects, where partners build confidence over time.
However, clarity still matters. Even when relationships are friendly, roles, expectations, and exit plans should be written down to avoid misunderstandings later.
When done properly, partnerships with capital-rich, time-poor individuals can feel less like fundraising and more like building a small, focused property business together—sharing risk, reward, and long-term momentum.
How Bridging Finance Works in Real Property Development Deals
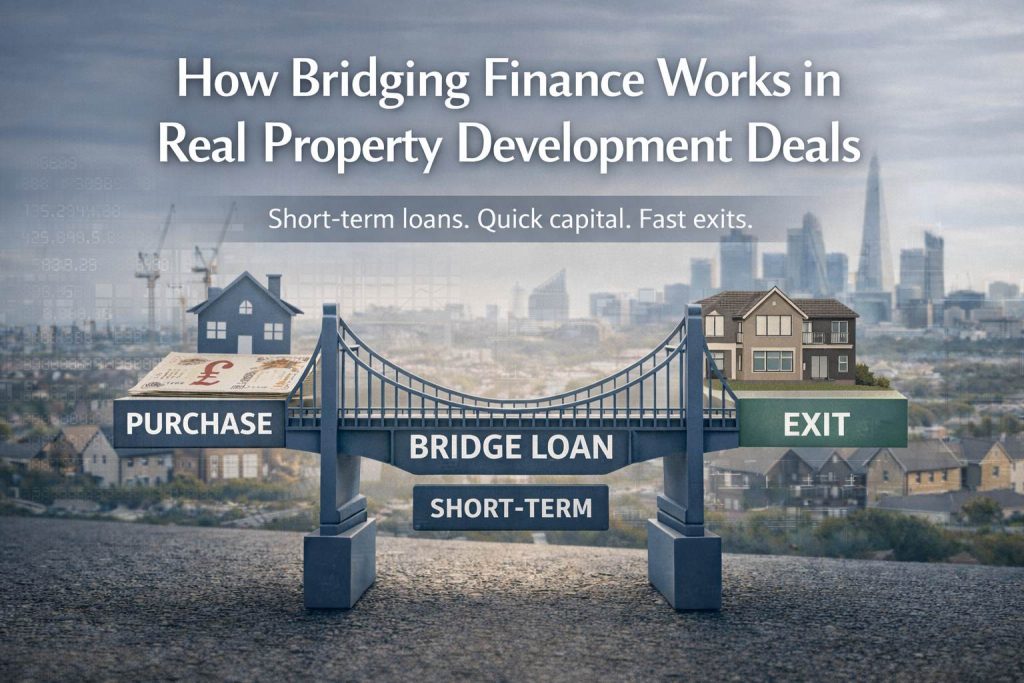
Bridging finance is the most common entry point into development — and the most misunderstood. In a typical buy-refurb-sell project, a bridging loan is used to:
- Acquire the property quickly (often within 7–28 days)
- Fund light to medium refurbishment works
- Hold the property short-term, usually 3–12 months
- Exit via sale, repaying the loan and interest from sale proceeds
Because bridging lenders focus more on the asset and exit strategy than personal income, approvals are generally faster and more flexible than standard mortgages.
Typical Bridging Loan Structure
For UK flipping projects, bridging finance is usually structured as follows:
- Loan-to-Value (LTV): Up to 70–75% of the purchase price
- Interest: Charged monthly (commonly 0.7%–1.2% per month)
- Term: 3 to 12 months (sometimes extendable)
- Security: First legal charge on the property
- Exit: Sale of the refurbished property
The exit must be defined from day one:
- Sale on completion, or
- Refinance onto a buy-to-let mortgage
Interest is often rolled up (added to the loan and paid at the end), which can help preserve cashflow during the refurbishment phase.
The real costs people underestimate
Beyond interest, bridging involves:
- Arrangement fees
- Broker fees
- Legal fees
- Valuation fees
- Higher insurance and utility costs
These costs disproportionately affect smaller deals.
Why Flippers Use Bridging Finance
Bridging finance is popular for flipping because it enables investors to:
- Move fast on below-market or distressed opportunities
- Buy properties that fail mortgage valuation or current UK property market conditions tests
- Complete auction purchases within strict deadlines
- Add value quickly without long-term finance restrictions
- Compete with cash buyers without holding full cash reserves
For experienced investors, the speed advantage alone can be the difference between securing a profitable deal and missing it.
Key Risks to Understand
While bridging finance is powerful, it must be used carefully. The main risks include:
- Higher borrowing costs than mortgages
- Time overruns on refurbishment increasing interest costs
- Exit risk if the property doesn’t sell as expected
- Valuation risk if resale value is over-estimated
This is why successful flippers place heavy emphasis on accurate purchase pricing, realistic refurb budgets, and conservative exit assumptions before using bridging finance.
Why time is the biggest risk with bridging loans
Bridging does not usually fail because finance is unavailable. It fails because projects overrun. Each extra month compounds cost and erodes margin — particularly dangerous when capital buffers are thin.
When Bridging Finance Makes Sense
Bridging loans are most effective when:
- The deal has clear value uplift potential
- The exit (sale) is realistic within 6–12 months
- The investor has experience or professional support
- The numbers still stack after interest, fees, and contingencies
Used correctly, bridging finance is not a last-resort product—it’s a strategic tool that enables disciplined investors to execute profitable flips that would otherwise be impossible using conventional lending.
Raising Capital Through Joint Ventures (What Actually Works)
Joint ventures are often presented as easy solutions. In reality, they demand clarity, discipline, and proper legal structure.
How a Property Joint Venture Usually Works
While structures vary, most UK property JVs follow a similar framework:
- The capital partner provides some or all of the purchase and refurb funds
- The operating partner sources the deal, negotiates the purchase, manages the works, and handles the sale
- A formal joint venture agreement defines profit splits, responsibilities, decision-making powers, and exit terms
- Profits are distributed after all costs are repaid, including capital return
In flipping projects, capital is often tied up for 6–18 months, depending on the complexity of the refurbishment and the resale timeline.
Common JV Structures in Flipping Projects
Joint ventures are flexible and can be structured in several ways, including:
- Profit split model (e.g. 50/50 after capital return)
- Preferred return model, where the investor receives a fixed return first, then remaining profits are shared
- Fixed uplift model, where the investor receives a defined minimum return regardless of final profit
- Equity-based JV, where ownership shares reflect capital and expertise contributions
The right structure depends on risk appetite, experience, and how involved each party wants to be.
Why Developers Use Joint Ventures
For active developers and flippers, JVs offer several advantages:
- Ability to scale without tying up personal capital
- Access to larger or multiple projects simultaneously
- Reduced reliance on high-cost short-term finance
- Alignment with investors who share a long-term mindset
- More flexibility than bank or bridging lenders
For many operators, JVs become the preferred route once they’ve proven a track record and want to grow beyond single-project limits.
Why Investors Choose Joint Ventures
From the investor’s perspective, JVs can be attractive because they offer:
- Exposure to property development returns without day-to-day involvement
- Potential returns higher than traditional buy-to-let
- Clear project timelines and defined exits
- Capital secured against real assets (depending on structure)
- Participation alongside an experienced operator
However, returns are not guaranteed, which is why due diligence on both the deal and the developer is essential.
Risks and Considerations
Joint ventures introduce a different type of risk compared to debt finance. Key considerations include:
- Partner risk – success depends heavily on the operator’s competence and integrity
- Cost overruns or delays impacting final profit
- Exit risk if market conditions change
- Legal clarity – poorly drafted agreements cause disputes
A robust JV agreement should clearly define:
- Capital contributions
- Profit distribution mechanics
- Decision-making authority
- Exit scenarios and dispute resolution
Without this clarity, even profitable projects can become problematic.
When Joint Ventures Make Sense
Joint ventures work best when:
- The deal has strong fundamentals and realistic margins
- The operator has a proven process for delivery
- Both parties understand the risks and timeframes
- Expectations on returns and control are aligned from day one
For many UK property developers, joint ventures are not just a funding method—they are a long-term business model that supports repeatable, scalable growth when traditional finance alone is too restrictive.
What private investors look for before committing funds
Investors expect:
- Evidence-backed purchase price
- Refurbishment scope and quotes
- Comparable sold prices
- Conservative GDV
- Clear timeline
- Full cost breakdown
- Defined exit strategy
They invest in specific deals, not general ambitions.
Legal protections investors expect to see
Standard protections include:
- Charge over the property
- Debenture over the SPV
- Solicitor-drafted JV agreements
- Defined exit and reporting obligations
These are normal and expected.
£25k vs £50k — How Starting Capital Changes Your Options
Starting capital fundamentally changes how risk behaves.
What £25k realistically allows you to do
With £25k–£30k:
- Purchase prices must be low
- Refurbishments must be light
- Timelines must be tight
- Margin for error is minimal
One delay or cost overrun can derail the project.
Why £50k gives flexibility rather than just bigger deals
With £50k:
- You can absorb delays
- Fund heavier refurbishments
- Negotiate better finance terms
- Reduce stress and decision pressure
How risk and margin for error differ at each level
£25k creates binary outcomes.
£50k allows recoverable mistakes.
This difference alone explains why many investors stall until capital increases.
When Development Finance Becomes Relevant (and When It Doesn’t)
Development finance is often misunderstood as the next logical step. It is not always appropriate.
Types of projects suited to development finance
Suitable projects include:
- Heavy refurbishments
- Conversions
- Multi-unit developments
- Ground-up builds
Funds are released in tranches and monitored by quantity surveyors.
Why development finance is often used too early
Early-stage developers underestimate:
- Equity requirements
- Professional fees
- Time risk
- Cost escalation
Used too early, development finance amplifies mistakes.
Can You Use Equity From Existing Property to Fund Development?
Equity extraction can work, but it is highly situational.
Remortgages, further advances, and second charges explained
- Remortgages: cheapest but slow
- Further advances: lender-dependent
- Second charges: faster but expensive
Common constraints investors face in practice
Recent purchases, higher-rate SDLT, and single-income affordability often limit borrowing more than expected.
Creative Purchase Structures That Reduce Capital Pressure
Sometimes capital pressure is reduced at purchase stage.
Delayed completion and long stop dates
Motivated vendors may agree to delayed completion, allowing time to raise funds or add value.
When vendor flexibility actually exists
These situations are rare and deal-specific. They require careful legal handling and cooperative vendors.
A Realistic Development Funding Strategy Using £25k–£30k
Limited capital demands discipline.
Choosing the right deal size
Lower purchase prices, strong resale demand, and simple refurbishments are essential.
Selecting the correct funding mix
- Bridging where cash allows
- JV structures where cash is constrained
Why one conservative deal beats multiple stretched projects
Stacking projects multiplies risk. One clean execution builds track record and confidence.
How the Strategy Changes With £50k Starting Capital
Capital changes behaviour as much as structure.
Increased buffers and reduced stress
Delays become manageable rather than catastrophic.
Improved negotiating position with lenders and investors
More equity attracts better terms and stronger confidence.
The Most Common Mistakes in Property Development Finance
Most failures are cumulative, not dramatic.
Underestimating costs and timelines
Small overruns compound quickly.
Assuming refinance exits will always work
Rental stress testing is essential.
Failing to structure deals properly from the start
Poor structure damages reputations and future funding prospects.
What You Need to Prepare Before Raising Any Capital
Preparation determines success.
The deal brief every investor or lender expects
A concise pack covering:
- Purchase price
- Refurb costs
- Comparables
- Timeline
- Risks
- Exit strategy
Why preparation matters more than pitching
Capital follows clarity.
£25k vs £50k Feasibility Calculator (Practical Framework)
Use this simple framework to test feasibility before committing.
Inputs
- Purchase price
- Deposit required
- Stamp duty
- Refurb budget
- Finance costs
- Timeline
- GDV
Rules of Thumb
- £25k deals must work with zero overrun
- £50k deals must survive 10–15% cost or time overrun
If a deal fails this test, walk away.
Flip Risk Scoring Tool (Quick Assessment)
Score each category from 1 (low risk) to 5 (high risk):
- Purchase discount
- Refurb complexity
- Planning risk
- Exit certainty
- Time sensitivity
- Capital buffer
Total Score
- 6–10: Low risk
- 11–18: Medium risk
- 19+: High risk (avoid with limited capital)
This tool forces discipline before emotion takes over.
Final Thoughts — How Property Development Is Really Funded
Most UK property developers do not start with large sums of money. They start with limited capital, conservative assumptions, and disciplined execution. The difference between stagnation and progress is rarely clever finance. It is choosing the right finance and deals that still work when timelines slip and costs rise.
Understanding how property development is actually financed allows investors to move forward with realism rather than aspiration — and that is what keeps projects, capital, and reputations intact.

Koye Beckley is a UK property investor and founder of UncommonDeal, with practical experience in buy-to-let, property auctions, refurbishment projects and investment deal analysis. Through UncommonDeal, he publishes property market research, property deal sourcing and compliance guidance, investment guides and data-driven analysis to help investors evaluate buy-to-let, BRRR, flip and auction opportunities.
